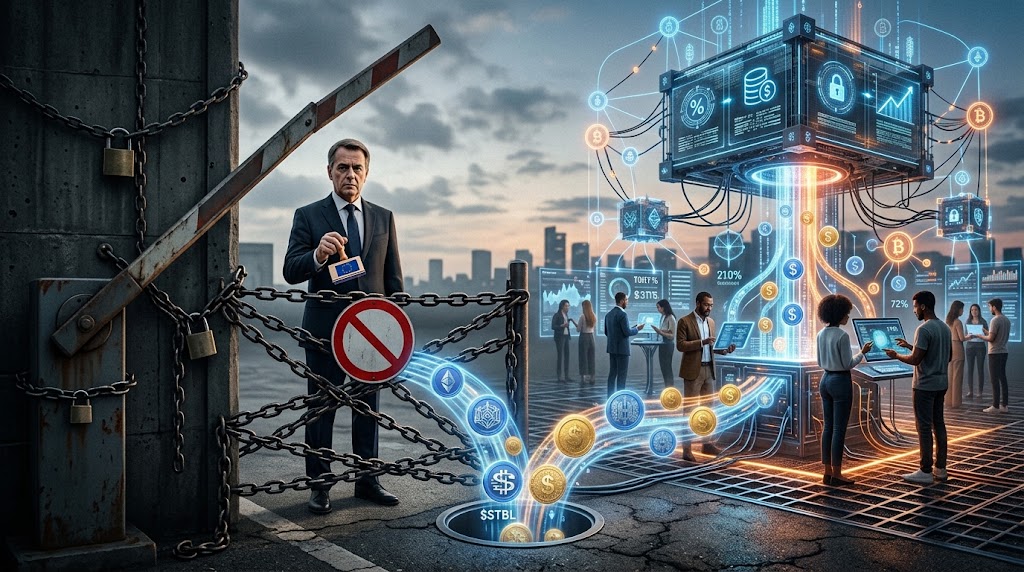
European policymakers evaluate digital assets through the outdated prism of commercial banking. Under current framework rules, Brussels prohibits paying interest on deposits for electronic money tokens, erroneously presuming that all financial returns originate from passive depository intermediation managed by central corporate issuers.
The debate demands immediate scrutiny following the European Commission consultation on MiCA. The European System of Central Banks formally recommended extending this prohibition directly to decentralized protocols, threatening to suppress euro-denominated liquidity against competitive global market venues.
Traditional banks collect liquid customer deposits to fund illiquid long-term debt through fractional reserves. Under that legacy structure, institutions incur significant duration mismatch, issuing loans while holding volatile liabilities. Bank interest compensates depositors for bearing balance-sheet credit exposure.
Challenging the central banks’ rigid approach, the European Securities and Markets Authority proposes proportionate disclosure rules instead for crypto lending activities. This recognition acknowledges that decentralized networks require operational transparency rather than broad statutory bans that misunderstand algorithmic mechanisms.
In decentralized finance, yield does not originate from executive promises or corporate discretion. Protocols function as automated liquidity markets where borrowers pay floating rates to access pooled assets. Users supplying capital maintain continuous on-chain property rights over their deposited collateral.
No money creation occurs out of thin air, nor does secondary credit multiplication exist. Every borrowed unit remains backed by verifiable excess collateral supplied in advance. Interest rates simply reflect the dynamic market clearing price for liquidity between independent protocol counterparties.
System integrity relies entirely on transparent code and algorithmic boundaries. When peripheral security flaws occur, such as technical risks in external adapters connected to peripheral pools, core contracts preserve deposited solvency without halting execution or requiring taxpayer interventions.
Should collateral values dip below predetermined safety ratios, liquidations trigger automatically in public mempools. There are no opaque balance sheets or regulatory lifelines. Conflating this autonomous structure with passive commercial deposits displays an erroneous appraisal of ledger infrastructure.
Consequences of regulatory overreach and market fragmentation
Civic engagement across Europe demonstrates widespread public resistance to sweeping yield restrictions. Over 50,000 European citizens submitted formal feedback to the Commission, while a parallel initiative gathered 126,600 signatures demanding access to legitimate rewards backed by productive reserves.
Regulatory data shows that only three stablecoins meet MiCA compliance among the top twenty-five tokens globally. Circle emphasized in its submission that suffocating legitimate returns will alienate European capital markets from international liquidity pools, restricting continental economic growth.
Banning yield will not diminish capital demand for productive returns. If European stablecoins are prohibited from integrating with decentralized lending pools, user capital will flow toward foreign jurisdictions and offshore dollar-backed tokens that facilitate permissionless lending mechanisms.
Financial records offer an instructive parallel with Regulation Q in the mid-twentieth century United States. By capping interest payments on domestic bank deposits by decree, federal regulators failed to extinguish investor yield demand, inadvertently triggering the expansion of the offshore Eurodollar market.
That artificial restriction drove massive balances away from domestic institutions toward flexible European financial centres. Today, the European Union risks repeating that outcome in reverse, expelling digital euro assets toward foreign regulatory hubs that recognize market-driven yields.
Decentralized developers engineered open protocols specifically to circumvent depository fragility. The design detailed in Aave documentation highlights how algorithmic overcollateralization in smart contracts protects depositor solvency continuously, dispensing with fractional reserve alchemy and discretionary administrative forbearance.
Yield across these liquidity markets represents dynamic utilization rates determined by real-time borrowing demand. Penalizing this protocol return as if it were a fraudulent inducement confuses organic peer-to-peer liquidity pricing with passive money market interest obligations.
The regulatory counterpoint and invalidation criteria
Central banking concerns stem from legitimate systemic anxieties. Monetary authorities worry that yield-bearing stablecoins could divert capital away from traditional credit creation, starving local businesses of essential financing while undermining established central bank interest rate transmission channels.
Furthermore, memories of opaque custodial lenders like Celsius warrant strict official caution. Those centralized enterprises offered high fixed interest while engaging in unhedged speculation, concealing balance-sheet deficits behind marketing slogans until liquidity evaporated during widespread market stress.
Assessing genuine distributed governance in decentralized finance remains essential to differentiate autonomous networks from centralized platforms masquerading as decentralized systems, ensuring protocol parameters reflect transparent community consensus rather than hidden operator control.
This analytical argument would break down if decentralized lending protocols abandon strict overcollateralization to pursue unhedged undercollateralized debt. Should bad debt accumulate without liquidation execution, protocol pools would replicate traditional banking insolvency risks during liquidity crises.
The thesis would likewise fail if licensed service providers offer contractually guaranteed fixed yields on deposited assets. In that scenario, the intermediary assumes corporate liability risk, justifying the full application of prudential reserve and capital requirements.
The practical consequences directly threaten European digital asset competitiveness. If the European Commission implements an expansive yield prohibition across all lending applications, euro-backed stablecoin issuance will likely stay depressed below two percent of total worldwide stablecoin supply.
Provided secondary platform incentives and peer lending remain accessible within American and global regulatory frameworks, capital migration will accelerate. Continental investors will use decentralized frontends to deploy dollar-denominated assets, bypassing domestic supervision designed to protect them.
Should European policymakers distinguish corporate deposit remuneration from overcollateralized lending yields, regulated euro tokens can expand on-chain adoption; otherwise, cross-border capital flows will demonstrate that restrictive rules favored institutional insulation over financial modernization.
This article is for informational purposes only and does not constitute financial advice.