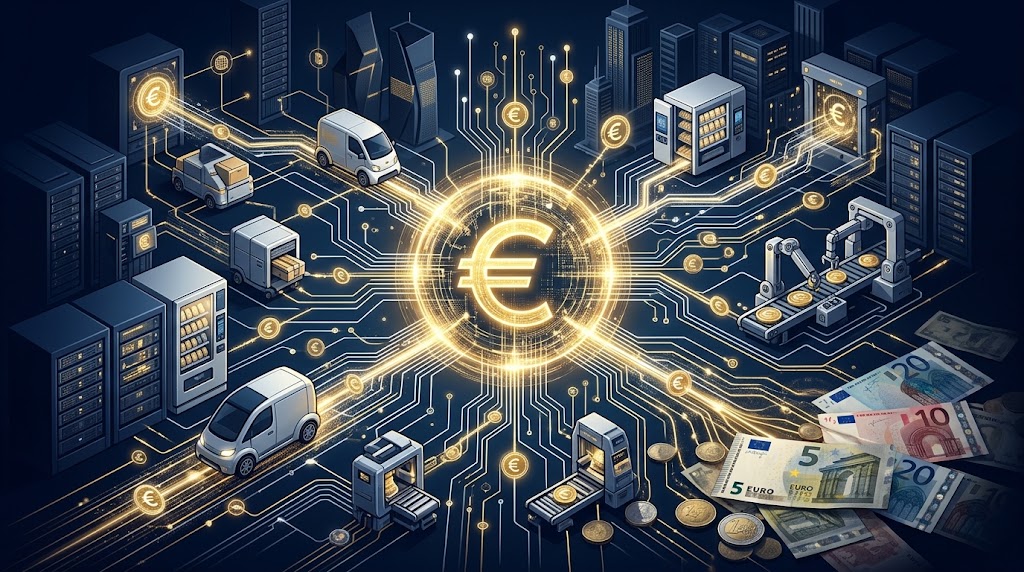
The European Central Bank is not merely seeking to update physical banknotes with its digital currency initiative. The monetary authority designs the official digital euro project portal to govern machine-to-machine transfers executed by autonomous industrial devices without manual intervention across member states.
Institutional communication frequently highlights a free public instrument for ordinary retail shopping across the single market. However, Frankfurt prioritizes automated settlement because private networks and American software giants are already positioning themselves to control high-frequency transactional rails across European manufacturing.
In June 2023, European policymakers published the regulatory package of the Commission to establish statutory operating standards for sovereign digital cash. That framework seeks to prevent foreign dollar-pegged stablecoins from dominating machine liquidity inside the European industrial economy.
Modern logistics facilities rely on thousands of interconnected sensors that pay for electricity and transport tolls autonomously. Conventional commercial cards impose flat transaction fees and settlement latencies that render continuous micro-transfers of cent fractions economically impossible between connected hardware units.
The central bank directly examined these programmatic capabilities during recent trials with artificial intelligence agents conducted alongside thirty-six commercial banking partners. Those technical experiments demonstrated that conditional payment logic can settle machine-driven equipment procurement within a few milliseconds.
If international technology platforms secure exclusive technical standards for autonomous machine transfers, European authorities will lose sovereign monetary control. Continental manufacturers would eventually pay substantial operating rents to proprietary clearing systems located completely outside European regulatory oversight.
Controlling the base currency for wholesale settlement remains vital for European strategic autonomy in high-tech sectors. Central bankers are therefore accelerating development schedules to connect public financial architecture with emerging automated computational environments across the European continent.
Privacy Tradeoffs in Programmed Machine Transfers
The formal statutory architecture is outlined in the legislative file on digital currency cataloged as COM(2023) 369. While the regulatory proposal expressly prohibits programmable money that restricts purchasable goods, it explicitly permits conditional payments executed via algorithms.
This semantic distinction obscures a structural challenge regarding transactional neutrality and privacy. Physical paper cash preserves absolute anonymity without requiring digital authentication or network permission to finalize exchanges between commercial counterparts in everyday economic activity.
The monetary authority acknowledged these operational tensions within the legal opinion of central bank issued in October 2023. The official document clarifies that anti-money-laundering compliance mechanisms require recording electronic transaction details once payment volumes exceed established regulatory thresholds.
Because autonomous hardware must verify cryptographic certificates and legal identities before transferring balances, the unconditional neutrality of cash disappears. The underlying ledger continually monitors asset destinations, turning a bearer instrument into an auditable and centrally supervised data channel.
This structural transition mirrors the launch of the Target settlement system in 1999, which unified European wholesale banking. That core infrastructure modernized cross-border interbank clearing, but it kept human treasury managers responsible for initiating and approving every significant institutional fund transfer.
Today, delegating discretionary execution to algorithmic systems extends rapidly into consumer markets, evidenced by portfolios managed by autonomous software for individual retail investors. Algorithmic software directly controls balance sheet distributions without requesting step-by-step human permission for every capital deployment.
Automated scripts analyze liquidity conditions continuously and distribute capital instantly according to preset parameters. This technical shift eliminates traditional boundaries separating commercial depository banking from fully autonomous programmatic execution across domestic and cross-border financial markets.
Industrial Counterpoint Against Private Settlement Rails
Advocates of public currency argue that only a central bank provides a neutral settlement foundation for industrial commerce. From their perspective, proprietary technology networks impose arbitrary tolls and closed protocols that damage small European manufacturers lacking bargaining leverage.
This defense remains valid regarding systemic stability and counterparty default risk. A technical outage or corporate insolvency within a private stablecoin issuer would paralyze automated factory assembly lines dependent on those proprietary tokens for daily parts delivery.
However, arguments defending public settlement dominance will fail if decentralized open protocols achieve frictionless zero-fee settlement. In that environment, industrial software developers will favor neutral global networks rather than state-administered platforms bounded by regional jurisdictions.
A severe operational obstacle stems from proposed individual holding caps, projected around 3,000 euros to safeguard private commercial deposits. If authorities enforce rigid limits, automated corporate treasuries cannot process the substantial capital volumes required by interconnected supply chains.
Autonomous logistics fleets or petrochemical refineries purchasing bulk raw materials would deplete statutory caps within seconds. Manufacturing enterprises would consequently adopt offshore synthetic stablecoins to keep automated production pipelines operational without disruptive artificial balance interruptions.
Lengthy European legislative timelines also create a strategic disadvantage against agile American commercial consortia. If international automakers standardize proprietary settlement architectures before European currency deployment finishes, continental institutions will struggle to attract enterprise machine volumes.
Describing this programmable infrastructure as an electronic equivalent of physical banknotes remains conceptually flawed. A digital ledger requiring verified identities, balance limits, and supervisory intervention operates like a restricted banking network, not like bearer cash.
Commercial lenders are simultaneously developing tokenized commercial bank deposits to protect their profitable lending franchises. This private bank initiative risks fragmenting corporate liquidity further, preventing the establishment of a single homogeneous payment standard across the European industrial base.
If European Union policymakers maintain restrictive holding caps and fail to establish unlimited corporate settlement channels before late 2027, the sovereign digital euro will capture less than five percent of autonomous industrial machine-to-machine payments.
This article is for informational purposes only and does not constitute financial advice.