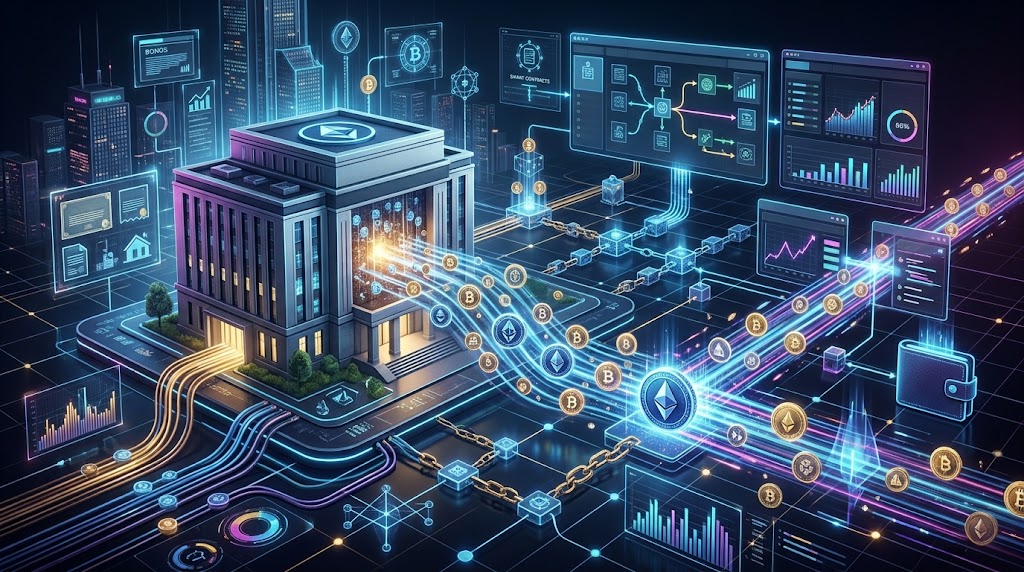
The financial debate around digital assets typically focuses entirely on retail speculation, ignoring technical advancements. However, the real impact lies in backend infrastructure that quietly supports the large-scale issuance and worldwide distribution of highly regulated institutional financial capital.
Replacing a transfer agent’s centralized database with a distributed ledger structurally alters operating costs. The World Economic Forum tokenization analysis report highlights how this digitization drastically cuts capital immobilization and democratizes secondary access.
The urgency behind this migration responds directly to a growing pressure to achieve operational efficiency and continuous liquidity across global markets. While traditional managers still rely heavily on delayed settlement cycles, the deployment of blockchain technology allows for guaranteed atomic transaction execution.
This direct technical shift clearly explains why securities tokenization gains vast institutional momentum. It fundamentally optimizes a fragmented legacy system that simply can no longer handle the extreme transactional speed demanded by modern capital.
For the institutional issuer, recording share ownership via a blockchain severely mitigates heavy administrative burdens. Smart contracts automatically assume strict regulatory compliance duties, actively verifying user identity, checking investment limits, and confirming overall investor eligibility before processing any cross-border financial transfer request.
The comprehensive annual Citi tokenization market report projects that digitized securities will reach five trillion dollars globally by 2030, primarily driven by the efficient removal of unnecessary intermediaries and subsequent operational cost reductions.
Flexibility and immediate availability represent the most crucial differences for the qualified investor. A conventional money market fund locks up capital over weekends or demands bureaucratic advance notices to process high-volume withdrawals, severely limiting maneuverability when reacting to immediate financial opportunities in volatile markets.
Conversely, a digitized investment vehicle facilitates direct peer-to-peer transfers anytime. The BlackRock institutional BUIDL digital liquidity fund, managing massive corporate assets, guarantees rapid subscriptions and redemptions utilizing continuous liquidity networks seamlessly.
Quantitative evidence and operational frictions
Current metrics demonstrate genuine financial adoption that far exceeds mere corporate proofs of concept. The official FOBXX government money fund page reports 720 million dollars in assets under management, directly administered on robust public network architectures rather than completely siloed private banking servers.
This pioneering government fund utilizes proprietary validation nodes to cryptographically record shareholder ownership in real time. This technological approach reduces extensive traditional settlement times, dropping from multiple business days down to mere seconds.
The structural modernization of the market is not limited exclusively to classic United States Treasury bills. Decentralized accounting architecture allows the steady yield of conservative assets to flow without major frictions into multiple financial ecosystems that are entirely native to the digital environment.
The fluid use of these instruments means tokenization firmly reshapes institutional credit markets, enabling fund shares to serve as instant collateral for international loans, entirely bypassing the rigid scheduling constraints of conventional banking.
The opposing stance within the corporate sector argues that digitizing an already regulated and highly liquid fund provides only a marginal improvement. Financial detractors firmly point out that this slight internal administrative optimization does not justify assuming the inherent technological risks associated with public blockchain networks.
These critics argue that the traditional American settlement system operates efficiently enough for the vast institutional majority. From that perspective, exposing large capital pools to potential smart contract flaws adds an absolutely unnecessary cyber risk vector.
This detracting argument holds complete analytical validity if the evaluation is strictly restricted to standard domestic trading executed during conventional business hours. However, the true disruptive value is not retail; it resides entirely in the technical programmability of money across global and heavily fragmented cross-border jurisdictions.
In regular international operations, financial clearing requires multiple business days and incurs high correspondent banking costs. It is precisely within these systemic bottlenecks where the distributed ledger definitively solves structural capital mobility problems.
Redefining the flow of capital
If the underlying financial assets maintain exact identities and yields in both models, the commercial competitive advantage shifts directly toward programmable utility. Traditional issuers that fail to integrate atomic settlement capabilities will face clear disadvantages when attempting to capture multinational corporate treasury allocations going forward.
Simplified direct access to international liquidity pools permanently alters corporate shareholder registry administration. Consolidating balances on shared ledgers decisively reduces the heavy corporate burdens closely associated with exhausting accounting verifications and routine daily reconciliations.
The strict automation of dividend payments through the implementation of self-executing code lines eliminates a massive amount of error-prone administrative processes. This operational shift makes it significantly easier for funds characterized by high daily turnover to maintain net profitability margins considerably higher than historical industry averages.
The definitive move toward immutable ledgers strongly diminishes informational fragmentation among custodians. By possessing a single unified database, continuous financial audits can be executed without pauses, guaranteeing maximum transparency regarding various monetary vehicle holdings.
Entry barriers are also significantly reduced for the secondary institutional corporate portfolio. The newfound capacity to fractionalize ownership without incurring disproportionate operational costs allows medium-sized managers to access restricted liquidity instruments that historically required massive capitalization minimums which were completely unfeasible for emerging financial entities.
If the opportunity cost of capital remains elevated due to persistently high interest rates, corporate treasurers will continue demanding continuous returns on parked liquidity. This macroeconomic pressure would force global managers to structurally migrate their funds toward permanently interoperable monetary networks before the decade ends.
This article is for informational purposes only and does not constitute financial advice.