Prolonged macroeconomic tightening has dismantled assumptions regarding crypto decorrelation from broader monetary policy. Peripheral capital suffers systematic drainage toward risk-free returns guaranteed by the Federal Reserve Federal Funds Rate, which has maintained nominal yields above 5% across extended contractionary monetary phases.
Market participants long assumed software utility alone would insulate decentralized protocols from sovereign bond dynamics. However, restrictive interest rates demonstrate that liquidity abandons experimental networks whenever fiat debt instruments provide positive real yields without technical protocol vulnerabilities or extreme price volatility.
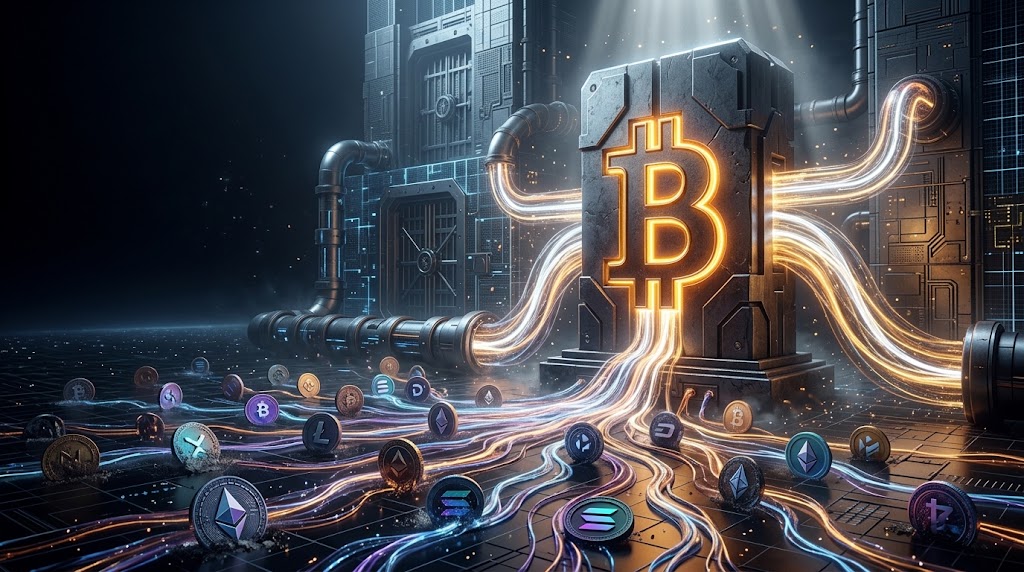
The divergence between the primary asset and secondary tokens stems from structural institutional plumbing. While spot exchange-traded vehicles approved by the U.S. Securities and Exchange Commission direct capital exclusively into Bitcoin, peripheral ecosystems remain isolated from conventional institutional balance sheets.
Regulated entities treat Bitcoin as digital collateral with predictable scarcity. As sovereign balance sheets acknowledge its monetary role, regulated inflows create structural support during broader financial corrections, a liquidity backstop entirely absent across decentralized finance and alternative layer-one ecosystems.
Secondary networks remain tethered to speculative retail dynamics. Evaluating whether Bitcoin is becoming more sensitive to traditional bond markets confirms that peripheral tokens carry higher drawdown risks during periods of elevated real yields and constrained central bank balance sheets.
Institutional Asymmetry and High-Beta Subordination
Staking yields fail to provide adequate risk premiums over risk-free benchmark instruments. Within Ethereum, baseline validation issuance documented across the Ethereum Foundation Whitepaper yields roughly 3% annually, which pales beside risk-free yields published by the U.S. Department of the Treasury.
Holding peripheral assets under restrictive macro regimes exposes portfolios to negative risk premiums once factoring smart contract exposure, lockup durations, and token depreciation. Consequently, asset managers reallocate capital toward fixed-income alternatives offering superior liquidity profiles and capital guarantees.
These structural constraints revive debates regarding execution layers. Analyzing who really decides Ethereum governance clarifies why decentralized roadmaps encounter adoption frictions when competing directly against yield-generating fiat instruments managed by traditional banking systems and institutional custodians.
Historical parallels illustrate this structural divergence. During the 2020 and 2021 liquidity expansion, unprecedented money supply growth subsidized speculative venture investments across smart contract platforms, driving nominal valuations higher despite negligible fee capture and low organic user retention.
Central bank balance sheet normalization reversed that dynamic. In a regime of credit scarcity, altcoins function as high-beta derivatives of Bitcoin: they suffer amplified drawdowns during macro adjustments while capturing an insignificant proportion of regulated ETF inflows.
The Utility Fallacy Under Credit Contraction
Network activity metrics remain secondary to global M2 contractions. For leverage-dependent operators, elevated beta accelerates portfolio liquidations whenever market volatility triggers automated collateral unwinds across thinly traded order books and decentralized automated market makers.
Liquidity across decentralized venues has fragmented across hundreds of competing protocols. Without aggressive token inflation subsidies, protocols incapable of generating sustainable organic fee revenue face substantial valuation multiple compressions against the monetary base of the network.
A counter-thesis suggests that current asset compressions precede genuine technological decoupling. Advocates argue that protocols generating sustainable fee revenue from transaction volume will retain enterprise capital regardless of benchmark interbank lending rates or sovereign debt yields.
This dissenting argument would prove accurate if stablecoin settlement demand and execution fees generated durable revenues exceeding sovereign bond returns, effectively establishing autonomous decentralized protocols as independent technology infrastructure businesses with sustainable real economic yield.
Nevertheless, institutional capital seeks safety first whenever sovereign yields exceed net staking rewards distributed by decentralized protocols. Without broad monetary easing, secondary tokens remain dependent upon internal speculative rotation rather than sustainable capital acquisition.
If central bank benchmark rates remain above 4% while ten-year sovereign bond yields maintain levels above 4.5%, the performance spread between altcoins and Bitcoin will continue to widen, penalizing protocols dependent on token incentives and unproven economic models.
This article is for informational purposes only and does not constitute financial advice.