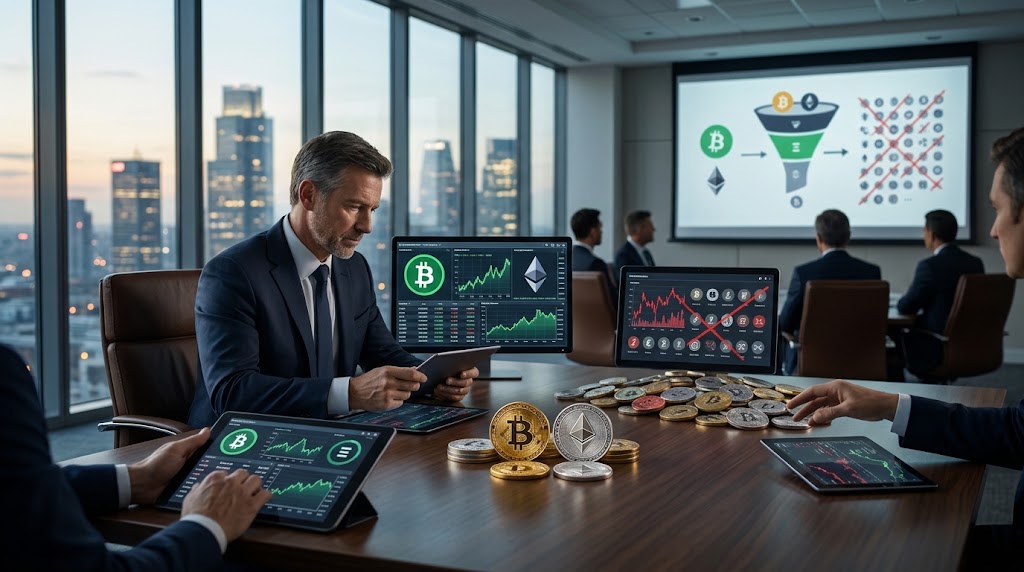
Institutional balance sheets do not allocate capital across thousands of digital assets. Conservative financial entities establish strict compliance filters that systematically exclude secondary digital assets from corporate balance allocations.
Mainstream commentary frequently assumes corporate treasury managers will lift every speculative project with active developers. However, institutional fiduciary duties dictate that institutional liquidity takes precedence over theoretical arguments regarding community governance.
Throughout the past decade, institutional custodians avoided digital asset exposure due to unhedged volatility. The authorization of spot exchange-traded funds shifted this landscape, directing deep capital flows exclusively into markets with verified historical liquidity.
Asset managers structure investment vehicles only through regulated custodians under strict governmental scrutiny. According to regulatory documentation released by the Securities and Exchange Commission, spot fund approvals required comprehensive surveillance agreements to mitigate manipulation risks.
This selective preference relies directly on quantifiable order book depth and settlement reliability. Traditional portfolio managers avoid experimental tokenomics, sudden emission changes, or decentralized architectures that lack proven stress-test records during liquidity squeezes.
Meanwhile, Ethereum occupies a separate functional niche directed toward smart contract execution. Institutional capital values its utility for programmable balance settlements rather than viewing it strictly as an absolute passive store of balance reserves.
A thematic stability paper published by the Financial Stability Board highlighted that severe market vulnerabilities concentrate within opaque decentralized governance structures. This analytical assessment keeps most decentralized platforms strictly outside tier-one banking balance integrations.
Specific payment protocols like the infrastructure built around XRP target corporate treasury liquidity and cross-border settlement. Their institutional adoption depends entirely on operational cost reductions for payment processors rather than retail market sentiment.
Traditional finance does not acquire entire decentralized architectures; it integrates individual technical capabilities that satisfy specific mandates. Assets without accountable legal counterparts or verified security audits are barred from institutional investment portfolios.
Compliance hurdles and capital concentration
Corporate capital allocators require legal certainty above speculative return projections. Investment committees penalize open-source protocols whose concentrated validator sets or early distributions create continuous exposure to regulatory litigation.
Empirical research conducted by the International Monetary Fund confirmed that correlation between digital assets and traditional equities increases as regulated derivatives mature. Digital tokens lacking regulated liquid derivatives cannot support professional hedging strategies.
Within this framework, blockchain infrastructure acts as a shared ledger exclusively if it connects directly with legacy banking messaging standards. Protocols unable to interface with existing financial networks remain confined to isolated retail trading venues.
Advocates of absolute decentralization argue that institutional gatekeeping undermines the foundational ethos of self-sovereign networks. They correctly point out that custodial intermediation reintroduces structural counterparty risks, censorship potential, and reliance on systemic entities.
This counterargument holds merit because centralized institutional intermediaries historically externalize catastrophic balance sheet failures. If traditional wrappers around digital assets replicate legacy leverage, the transparency benefits of distributed ledgers disappear for end users.
Furthermore, this thesis of narrow adoption would fail if international regulators standardized privacy-preserving auditing solutions at scale. Enterprise adoption of compliant zero-knowledge proofs would allow non-custodial networks to bypass current centralized compliance bottlenecks.
Present capital adequacy rules force regulated banks to apply punitive risk weightings to unbacked crypto holdings. Consequently, treasury desks limit collateral acceptance to protocols possessing decade-long operating records and documented regulatory standing.
Institutional capital allocations demonstrate that integration acts as an aggressive filtering process. While a minimal subset of assets solidifies treasury presence, thousands of speculative tokens face chronic drying of trading volumes.
If international banking supervisors maintain maximum risk-weight penalties on unhedged crypto exposures, more than ninety percent of enterprise market liquidity will remain locked within the top two digital assets over the next three fiscal cycles.
This article is for informational purposes only and does not constitute financial advice.