The technical criticism voiced by Tangem regarding access to its payment card exposes an institutional contradiction: true transactional demand does not align with the geographic footprint permitted by regulated banking partners.
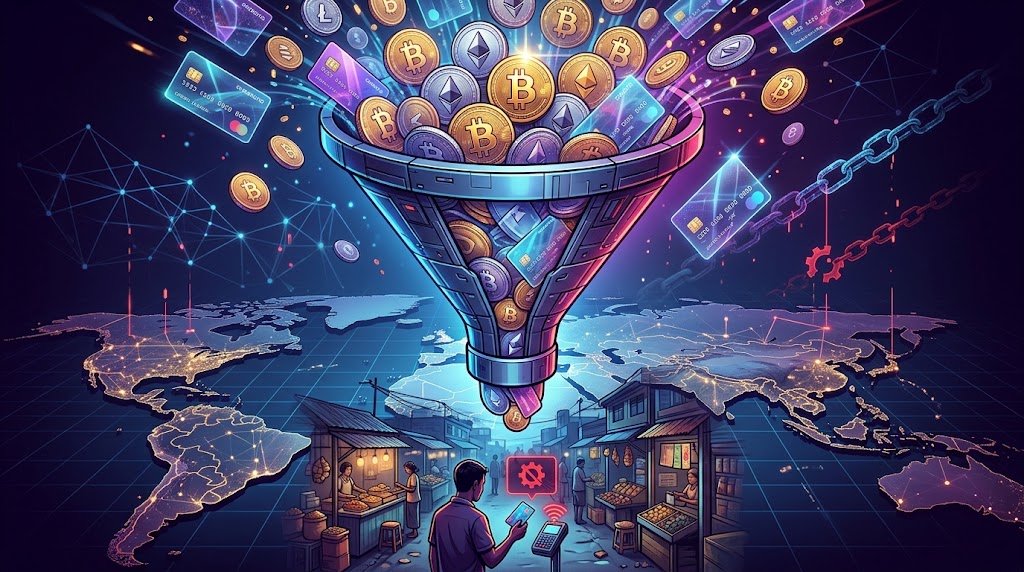
Everyday retail spending using digital assets remains obstructed across developing nations due to traditional payment conservativism. While stablecoins alleviate local currency devaluation, multinational payment networks concentrate products where protection against monetary debasement is least needed.
The manufacturer Tangem Pay confirmed that its Visa-backed physical and virtual card faces strict country restrictions that exclude most unbanked users located across the Global South.
This structural separation harms local economies and households that rely on Blockchain technology daily to safeguard disposable income against severe domestic currency depreciation.
The mismatch between defensive savings and licensed banking
In Latin America, Africa, and Southeast Asia, stablecoins function as real-time value storage. Citizens hold them to protect monthly earnings, yet purchasing groceries or medicine still requires cumbersome peer-to-peer (P2P) fiat off-ramping.
Official inclusion data compiled by the World Bank shows that 1.4 billion adults remain unbanked worldwide, held back by systemic documentation barriers and high maintenance costs within legacy financial frameworks.
For this demographic, manual conversion incurs substantial spreads, delays, and account freeze risks triggered by algorithmic bank alerts on ordinary informal transactions.
Historically, retail payment systems achieved scale only when manual frictions were eliminated, mirroring how magnetic stripe cards in the 1970s replaced physical paper checks with automated merchant terminal clearings.
Efforts to replicate that ease for crypto encounter strict compliance barriers. Detailed standards published by the Financial Action Task Force (FATF) impose stringent cross-border customer verification obligations on virtual asset providers.
Under this framework, licensed card-issuing partner banks restrict card distribution strictly to low-risk regions, intentionally sidelining emerging countries where retail crypto volumes reflect essential survival needs.
Macroeconomic tracking conducted by Chainalysis demonstrates that emerging economies lead worldwide adoption when measuring stablecoin purchasing volumes against gross domestic product per capita.
Nevertheless, partner banks affiliated with Visa and Mastercard continue prioritizing product rollouts across North America and Europe, where domestic fiat currencies are stable and banking penetration is virtually universal.
Compliance boundaries versus consumer spending autonomy
The opposing institutional perspective argues that restrictive distribution is not arbitrary negligence, but a necessary compliance measure driven by rigorous anti-money laundering frameworks and fraud prevention.
Legacy payment networks operate under disparate territorial regulations, fragmented foreign exchange rules, and strict domestic reporting mandates that inflate operational risk across developing countries.
This risk perspective carries weight: deploying instant crypto-to-fiat conversion debit cards with self-custody components exposes issuing banks to cross-border capital flight penalties and international sanctions scrutiny.
The premise that payment cards are essential for retail crypto adoption would be invalidated if native Defi rails build decentralized merchant processing layers that bypass card networks entirely.
Card access will expand to underserved regions if partner banks adopt tiered compliance frameworks calibrated for low-value retail purchases, allowing stablecoins in emerging markets to transition directly from informal swaps to commercial point-of-sale terminals.
This article is for informational purposes only and does not constitute financial advice.