The incorporation of decentralized digital assets into state treasuries directly challenges classical monetary management. Grounded in a purely peer-to-peer monetary design, the asset provides a mathematically fixed issuance cap against sovereign debt expansion. However, formal national adoption introduces severe operational friction regarding public liquidity and macroeconomic governance.
Institutional consensus has long prioritized foreign sovereign debt and liquid currencies to support balance-of-payments stability. Yet persistent worldwide fiscal deficits and bilateral currency diversification efforts are currently pushing digital asset custody from academic speculation into serious legislative and treasury debates.
Major financial institutions now consider structural shifts in sovereign portfolio construction over the coming decade. Research indicates possible central bank sovereign reserve holdings emerging before 2030. Holding unbacked scarce digital assets could theoretically counter purchasing power degradation across standard fiat debt instruments amid persistent fiscal stress.
Legislative interest reached formal consideration in Washington during July 2024 through dedicated statutory initiatives. A prominent legislative proposal in United States outlines purchasing up to one million coins across five years. The statutory text mandates holding accumulated balances for twenty years to strengthen federal solvency.
Historically, central bank reserves relied on rigid bullion convertibility agreements. After the disintegration of Bretton Woods in August 1971, monetary authorities substituted gold with foreign treasury obligations, binding international reserves directly to the fiscal health and geopolitical decisions of major reserve-issuing nations.
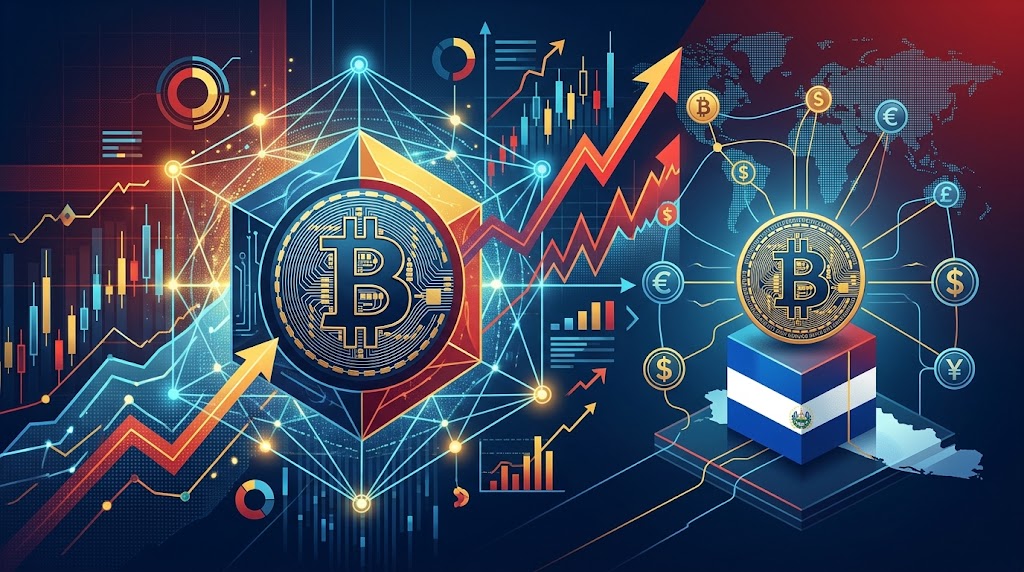
El Salvador became the first nation to mandate statutory legal tender status in September 2021. However, repeated International Monetary Fund policy assessments underscored substantial fiscal exposures and liquidity hazards. These critiques prompted authorities to confine treasury transactions in subsequent multilateral debt negotiations.
Official figures indicated El Salvador accumulated over 5,800 units by mid-2024 through daily acquisition protocols. While unrealized balance sheet gains surfaced during market rallies, everyday commercial transactions among domestic citizens remained exceptionally modest according to domestic central bank surveys.
Sovereign Balance Sheet Realignment and Supply Dynamics
Sovereign accumulation fundamentally alters secondary crypto markets by locking coins into cold storage vaults under multi-year mandates. Removing substantial circulating supply from exchanges reduces liquid order books, materially amplifying price volatility whenever traditional institutional capital or commercial funds enter spot trading venues.
Market pricing displays acute sensitivity to foreign policy shifts and security friction. Trading data showed geopolitical volatility driving market swings above critical valuation levels. Such swings demonstrate that strategic crypto reserves absorb intense market sentiment rather than operating as inert monetary anchors.
Financial regulators express concern regarding structural interlinkages between digital assets and commercial banking systems. Detailed Federal Reserve financial stability research highlights how abrupt asset depreciations spread through intermediaries. Without strict ring-fencing, severe balance sheet contractions could destabilize broader sovereign credit metrics.
Funding a national reserve requires tax revenue surpluses, foreign exchange conversions, or new debt issuance. In economies running structural deficits, issuing sovereign debt to purchase volatile tokens compounds interest burdens on taxpayers during periods of restrictive global monetary policy.
The creation of a formal national reserve by a leading economic power would trigger competitive game theory dynamics. Rival states would face immediate pressure to accumulate reserves before market repricing eliminates parity, initiating an uncoordinated scramble for digital collateral.
Government accumulation also contradicts the founding decentralization ethos of public blockchain architectures. When sovereign treasuries control substantial portions of total coin supply, state actors gain disproportionate influence over trading depth and validator economics, potentially compromising neutral market access for private international participants worldwide.
Fiscal Fragility, Sovereign Debt, and Invalidation Criteria
The opposing analytical perspective maintains that high price volatility disqualifies digital assets from reserve status. Central banks require predictable liquidity buffers to defend domestic currencies. Holding volatile assets subject to severe cyclical drawdowns jeopardizes import cover metrics during acute balance-of-payments shocks.
This critique carries substantial weight for developing nations facing tight borrowing limits. Committing treasury capital toward speculative reserves imposes steep opportunity costs against urgent domestic infrastructure needs and pressing external debt servicing.
A structural execution paradox emerges during acute sovereign fiscal stress. If a distressed treasury must liquidate significant token holdings to meet imminent foreign debt maturities, large-scale spot sales depress market prices, destroying the salvage value of remaining state reserve balances.
Public accounting standards lack unified frameworks for recording volatile digital assets. Furthermore, cold storage demands advanced multi-signature cryptographic protocols that most national auditing bodies cannot independently inspect or verify with established procedures.
The strategic reserve thesis would be invalidated if the asset’s correlation with broader equity markets converges toward 1.0 across full business cycles. Sustained synchronization would eliminate diversification benefits, reducing state holdings to mere high-beta risk assets lacking defensive reserve utility.
Similarly, cryptographic vulnerabilities in foundational signing algorithms or sustained protocol consensus splits would undermine network trust, destroying the theoretical foundation required for central bank balance sheet recognition.
Geopolitical fragmentation continues to spur interest in neutral monetary assets. In an era where traditional sovereign reserves can face international asset freezes, non-aligned governments actively study unseizable digital alternatives to preserve trade independence.
To balance these structural trade-offs, prudent policy frameworks recommend capping sovereign exposure within 1% to 3% of total reserves. This threshold insulates national finances from extreme market contractions while capturing potential sovereign appreciation.
If at least two investment-grade sovereigns allocate more than 1% of foreign reserves to digital tokens over the next five years while thirty-day rolling volatility drops below 40%, then sovereign bond spreads for participating nations will reflect reduced debt risk premiums.
This article is for informational purposes and does not constitute financial advice.