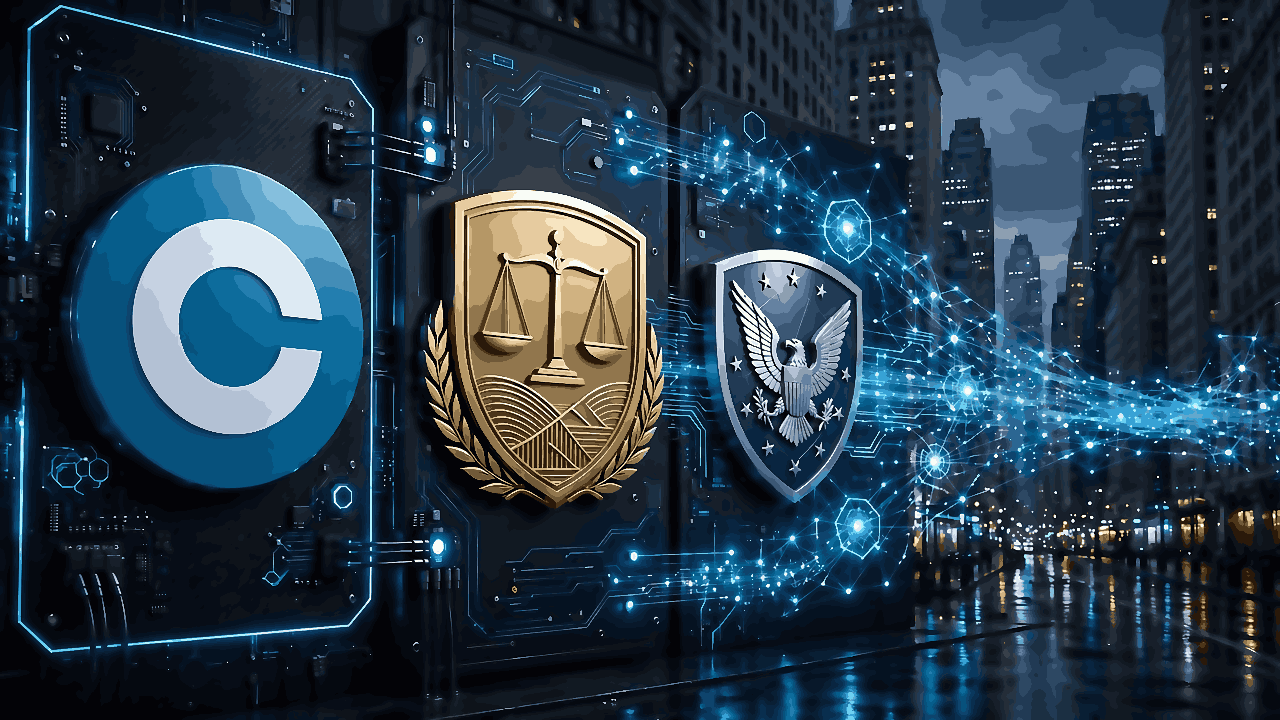
When Arthur Hayes co-founded BitMEX and introduced perpetual swaps in 2016, U.S. regulators viewed the experiment as a fringe anomaly. In November 2026, Hayes stated he felt flattered watching Coinbase, Kalshi, and Payward (Kraken’s parent company) defend in New York the Commodity Futures Trading Commission’s (CFTC) approval to list perpetual futures on individual U.S. equities.
Rather than being absorbed by traditional finance, crypto exports its financial infrastructure to modernize the American stock market. Conventional commentary assumes Wall Street is gradually digesting digital assets through exchange-traded funds and bank custody. Yet the lawsuit filed by the Capital Markets Alliance Association (CMAA) exposes the exact opposite dynamic. Incumbent players like Cboe and Citadel Securities turned to federal court to halt non-expiring contracts tied to single corporate stocks.
This legal offensive shows that established intermediaries recognize a direct competitive threat in crypto-native market design. The turning point unfolded in November 2026 inside the docket of Capital Markets Alliance Association v. CFTC. Although Judge Valerie Caproni denied a temporary restraining order due to the absence of immediate irreparable harm, she noted that plaintiffs are likely to succeed on the statutory merits.
The CMAA argues that under Title 7 of the U.S. Code, a futures contract requires delivery at a fixed future date. Consequently, it contends that an instrument without expiration must be regulated as a security-based swap under the exclusive jurisdiction of the Securities and Exchange Commission (SEC).
The regulatory response caught incumbent plaintiffs off guard. On November 10 and 11, the SEC itself filed a court brief opposing a trading freeze and supporting the CFTC’s jurisdiction.
Simultaneously, the coalition where Coinbase and Kalshi back CFTC in lawsuit over stock perpetual futures brought together Payward, DRW Holdings, Jump Trading, and Paradigm. These firms pointed out that both agencies had already issued a joint request for comment on swaps and alternative compliance in June 2026.
The Structural Redesign of Equity Liquidity
To understand why perpetual futures alter Wall Street’s equilibrium, it helps to trace their conceptual origin. In 1992, economist Robert Shiller proposed in the Cowles Foundation discussion paper on perpetual futures a daily cash-settled contract designed to track continuous cash flows.
The concept sat dormant for over two decades because legacy clearinghouses relied on quarterly expiration cycles and restricted banking hours. Crypto financial engineering solved that bottleneck through periodic funding rates, which tether the derivative’s price to the underlying spot market without rolling positions.
While Coinbase Financial Markets offered five-year dated hybrid contracts in July 2025, Kraken Derivatives US expanded to dozens of continuous contracts spanning equities and commodities. At the same time, decentralized venues already illustrate how RWA perpetual futures near parity with Bitcoin volume on Hyperliquid and Binance.
This transition eliminates liquidity fragmentation across multiple expiration months and lowers operational costs. Continuous trading without expiration delivers real-time margin adjustments compared to twentieth-century settlement windows.
The Statutory Objection and Thesis Limits
Still, the legal objection raised by the CMAA and advocacy groups like Better Markets warrants serious scrutiny. Their statutory argument is not mere protectionism: the Commodity Futures Modernization Act of 2000 drew a strict boundary between security futures and over-the-counter swaps.
If a contract lacks a future delivery obligation, classifying it as a traditional future stretches existing statutory text in ways the New York district court has already questioned preliminarily.
Furthermore, permitting continuous leverage on single stocks outside traditional broker-dealer rules introduces concrete systemic risks. During the more than $10.3 billion in liquidations recorded in October 2026 across decentralized venues, market data showed that continuous leverage amplifies liquidation cascades when liquidity thins.
Should Judge Caproni grant a preliminary injunction following December 2026 replies, or should the Second Circuit rule that the CFTC exceeded its statutory mandate, the thesis of immediate adoption would be invalidated and require congressional legislation.
Despite that procedural hurdle, the technical shift is unmistakable. When legacy exchanges litigate to block a contract structure invented ten years ago for Bitcoin trading, digital market operating standards are already redefining the competitive rules of the next decade.
The outcome of this legal battle will dictate the pace of financial convergence. If the federal court denies the CMAA’s preliminary injunction before the end of the first quarter of 2027 and monthly trading volume in single-stock perpetuals on CFTC-regulated venues surpasses 15% of equivalent single-stock options volume, it will demonstrate that crypto design is progressively displacing legacy equity conventions; conversely, a judicial reclassification as security-based swaps will confine these instruments to institutional counterparties.
This article is for informational purposes only and does not constitute financial advice.