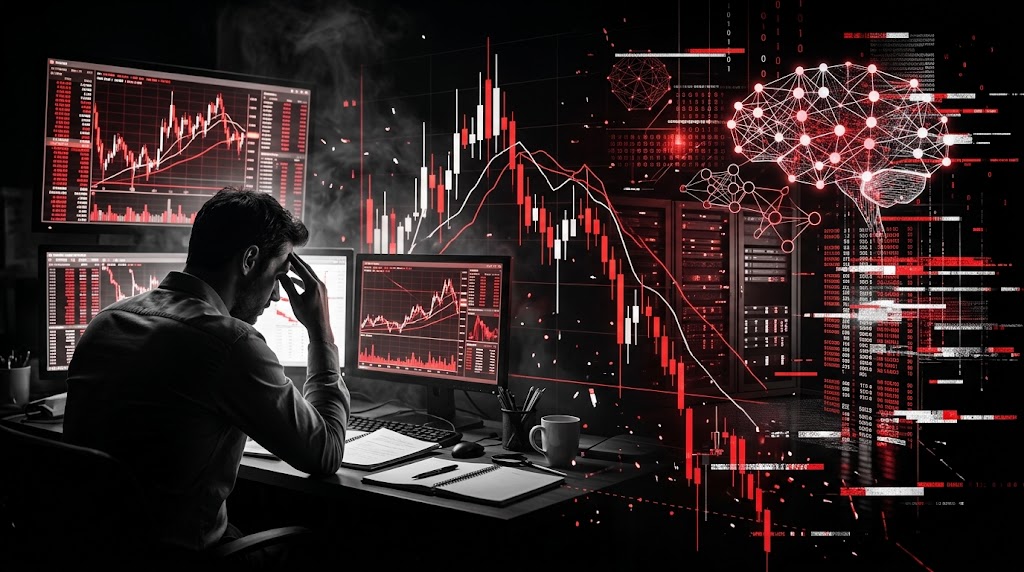
The widespread expectation that neural networks can forecast digital asset valuations encounters the mathematical limits of deep learning amid extreme volatility. While quantitative commercial platforms advertise algorithmic superiority, empirical directional accuracy remains severely bounded by non-stationary noise within decentralized financial time series.
Institutional allocators increasingly confront this dilemma as automated capital deployments expand across liquid digital exchanges. Determining whether programmatic architectures outperform human discretion is essential to prevent severe capital misallocations during unforeseen liquidity contractions across digital asset markets.
Modern quantitative trading strategies deploy diverse computational frameworks, including Long Short-Term Memory networks, gated recurrent units, temporal Transformers, and gradient-boosted decision trees like XGBoost. These architectures parse continuous order book feeds, high-frequency tick data, and raw on-chain transaction metrics.
In parallel, natural language processing pipelines such as FinBERT evaluate sentiment across social communities and media wires in milliseconds. This computational infrastructure detects shifts in participant positioning far faster than any manual chartist operating in conventional spot markets.
Processing statistical correlation, however, does not represent genuine economic comprehension. Machine models trained on past data assume underlying statistical stationarity across distributions that experience frequent structural regime breaks whenever sovereign monetary policies shift or international regulatory actions emerge.
This divergence marks a fundamental operational boundary. While automated neural systems process historical technical variables, human intuition contextualizes market anomalies effectively. Seasoned portfolio managers interpret geopolitical developments and regulatory inflection points that mathematical models cannot infer from pricing sequences alone.
Empirical Accuracy Versus Operational Friction
Conversely, human decision-makers suffer from behavioral vulnerabilities, emotional exhaustion, and cognitive heuristics during severe downturns. Discretionary traders frequently succumb to panic selling or risk aversion during abrupt market corrections, committing tactical errors that systematic code executes without sentiment.
Empirical academic literature provides sobering evidence regarding this technological rivalry. Multiple peer-reviewed studies indicate that while statistical learning architectures demonstrate short-term directional advantages across high-frequency intraday windows, predictive performance deteriorates rapidly when projecting across multi-day or monthly evaluation intervals.
In an empirical investigation published by Bilkent University examining liquid digital assets, the predictive accuracy of these algorithms achieved between 55% and 65% directional accuracy on minute-level horizons. However, this statistical premium eroded substantially once exchange fees, order book slippage, and spread latency were factored into net trade returns.
The precedent of Long-Term Capital Management in 1998 demonstrates the structural vulnerability of relying entirely on quantitative patterns. The firm failed when mathematical distribution models broke down during systemic stress, proving that past correlations cannot insulate portfolios against unprecedented liquidity seizures.
This dynamic persists in decentralized financial environments today. When programmatic algorithms interface with decentralized prediction market protocols, automated models encounter shallow order books where modest transaction sizes distort calculated probabilities, creating severe execution deviations from theoretical projections.
Proponents of computational automation maintain that machine architectures successfully eliminate execution hesitation during market panics. This position holds that automated systems process microstructural signals within microseconds, capturing short-lived price discrepancies before discretionary traders can respond manually.
While valid in high-frequency venues with sufficient market depth, this logic falters during broader liquidity drains. When competing algorithms attempt to exit positions using identical technical parameters, order routing congestion generates severe execution slippage that erases expected statistical gains.
Structural Limitations and Systemic Market Fragility
A staff research study from the Federal Reserve Board highlighted that algorithmic automation strengthens behavioral co-movement across quantitative desks. When institutional algorithms share similar statistical features, simultaneous liquidation signals trigger cascading market selloffs rather than orderly price adjustments.
Academic research in the Journal of Financial and Quantitative Analysis documents that tracking technical momentum in digital assets across 3,000 tokens yields discernible directional patterns. Yet the authors observe that real-world trading frictions reduce net profits markedly below raw econometric projections.
The core argument regarding predictive accuracy would be invalidated if autonomous machine models consistently demonstrated positive risk-adjusted returns during unexpected macro downturns, beating traditional buy-and-hold baselines after factoring in slippage and transaction costs over multi-year evaluation cycles.
Present empirical data instead indicates that predictive models excel in stationary regimes with established liquidity corridors, but underperform when unexpected legal actions, regulatory enforcement decisions, or major credit shocks alter broader market sentiment.
Data feed integrity presents an additional structural vulnerability. In decentralized finance ecosystems, risks like systemic financial oracle manipulation distort baseline price references, prompting automated algorithmic protocols to execute flawed liquidations based on compromised inputs engineered by malicious market participants.
A hybrid operational methodology offers the most robust solution for digital asset risk management. While recurrent neural networks identify microstructural liquidity inefficiencies continuously, human oversight committees must maintain control over exposure thresholds and macroeconomic positioning during turbulent cycles.
This dual structure mitigates statistical overfitting, a prevalent issue where complex algorithms mistake historical market noise for enduring physical laws. Human analysts filter out spurious mathematical signals that lack backing from fundamental network usage metrics or macroeconomic realities.
If digital asset trading platforms sustain cross-asset correlations exceeding 70% during acute stress episodes, algorithmic price forecasting will remain restricted to ultra-short execution intervals rather than serving as reliable tools for medium-term portfolio valuation.
Sustained capital preservation will consequently depend on dynamic position sizing calibrated to available market liquidity, positioning advanced computing as an analytical filtering engine rather than an infallible forecasting mechanism.
This article is for informational purposes only and does not constitute financial advice.