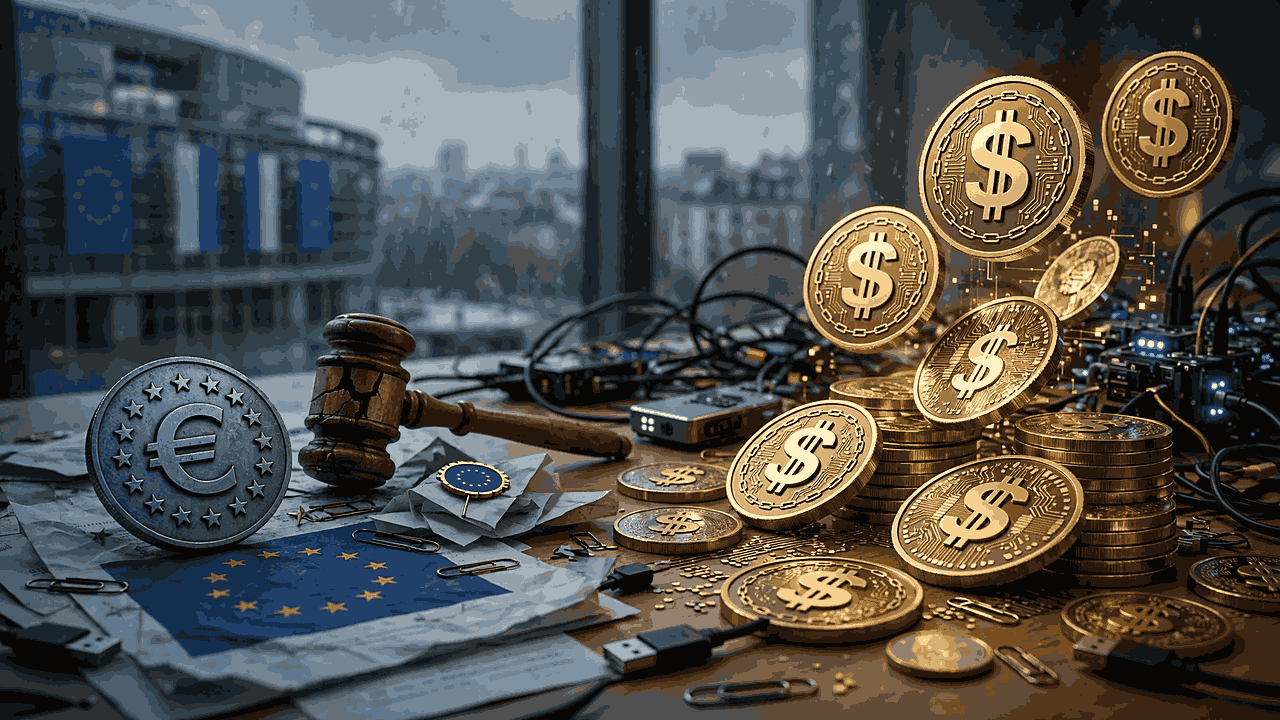
The European Union faces an imminent threat to its monetary sovereignty in retail finance. Brussels legislative paralysis harms competitiveness by delaying the issuance of the digital euro beyond 2029, entrenching deep operational reliance on foreign payment rails and private financial instruments.
European institutions originally promoted a central bank digital currency to preserve monetary autonomy in cross-border commerce. Yet that strategic objective now faces legislative friction and banking resistance, creating an institutional void that private market actors have successfully exploited across global digital ecosystems.
Piero Cipollone delivered a direct assessment during his parliamentary committee speech, noting that the deployment schedule depends entirely on political consensus. If lawmakers fail to enact the regulatory framework on time, technical preparations will stall before entering public infrastructure deployment.
The underlying metrics illustrate a stark reality. Dollar-backed stablecoins, led primarily by USDT and USDC, currently command more than 90% of global on-chain transactional volume, supported by an aggregate market capitalization exceeding 200 billion dollars in active circulation.
European policymakers observe this structural dominance while their own public solution remains confined to sandbox environments. While technical teams develop the digital euro pilot stage, global institutional and retail participants settle billions in private dollar-denominated assets across global networks without regulatory bottlenecks.
Frankfurt has conducted technical trials to demonstrate architectural capabilities. The central bank analyzed how the ECB designs autonomous payments for direct machine-to-machine settlements, yet these demonstrations lack operational authority without a comprehensive regulation formally approved by European legislative bodies.
Strategic autonomy hindered by domestic politics
European payment history reveals an enduring systemic pattern. For decades, member states allowed private American payment networks like Visa and Mastercard to dominate card settlement infrastructure, a structural reliance that EU leaders repeatedly promised to eliminate in next-generation financial architectures.
However, strict oversight rules under the markets in crypto assets regulation have produced unintended side effects. Instead of nurturing local payment alternatives, rigorous operational constraints have slowed down the issuance of euro-denominated stablecoins by private regulated institutions across the continent.
Persistent disagreements surrounding user privacy have further delayed statutory progress. Heated debates between law enforcement demands for comprehensive transaction traceability and citizen expectations for offline privacy standards have paralyzed core architectural decisions among key members of parliament.
Simultaneously, commercial banking groups have successfully advocated for individual holding limits between 3,000 and 4,000 euros. Strict caps reduce utility for commercial treasuries and institutional settlement, eliminating the practical incentives required to drive organic corporate adoption at scale.
Commercial lenders defend these holding caps on clear prudential grounds. They argue that unrestricted central bank digital balances could drain customer deposits during banking panics, severely increasing capital costs and restricting credit availability for European small businesses and residential mortgages.
While this financial risk is legitimate, it leaves the currency competitively disabled. An asset restricted by strict holding limits and stripped of native smart-contract execution cannot compete against private tokens backed by liquid reserves operating uninterrupted across open protocols worldwide.
Corporate developments reflect this ongoing friction. Even as the ECB tests digital euro architecture with financial counterparties, multinational corporations continue integrating private stablecoins into their cross-border supply chain settlements because of lower frictional costs and immediate liquidity.
The strategic price of trailing technological adoption
Regulatory delay does not merely alter calendar dates; it shapes long-term user behavior across payment systems. Private stablecoins capture market share across international remittances and tokenized asset settlements, establishing deep liquidity moats that sovereign instruments will struggle to dislodge in subsequent years.
The euro remains the second most important global reserve currency, accounting for approximately 20% of foreign exchange allocations. In contrast, its footprint across decentralized financial protocols and stablecoin market capitalizations remains insignificant, hovering well below 1% of total issuance.
This liquidity divergence institutionalizes de facto currency substitution on next-generation digital networks. If European authorities delay launch timelines until 2030, institutional treasurers and payment providers will have completed infrastructure migration toward existing private rails, rendering late public alternatives largely redundant.
This thesis will find confirmation if, following the conclusion of 2027 without adopted legislation, euro-pegged stablecoin volume remains below 2% of total digital token turnover against entrenched dollar instruments. Conversely, if Brussels enacts enabling legislation before 2027 granting flexible liquidity caps and autonomous execution, sovereign euro infrastructure may successfully reassert its position within European enterprise settlements.
This article is for informational purposes only and does not constitute financial advice.