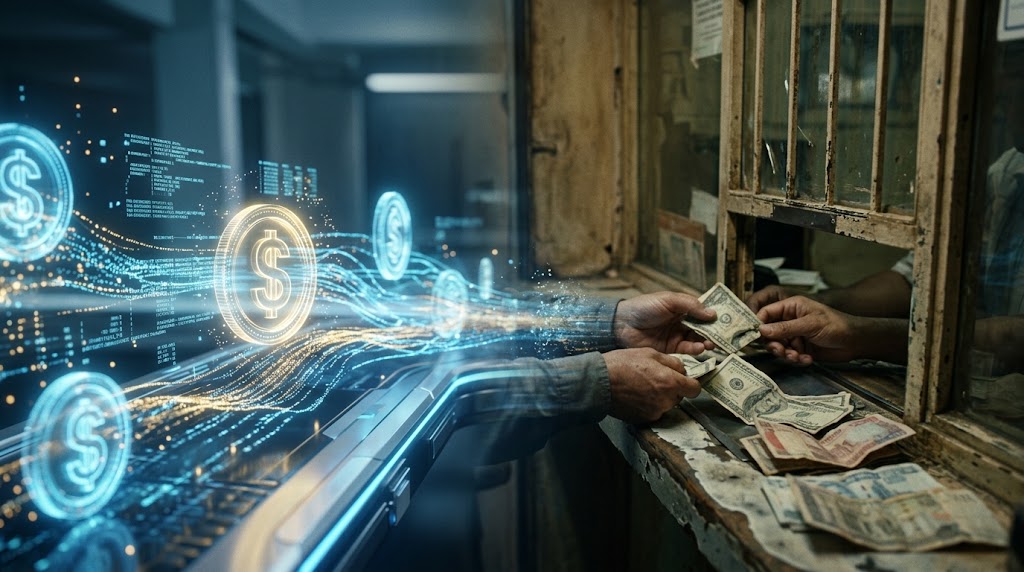
The Borderless.xyz technical research report revealed that transferring two hundred dollars through decentralized ledgers carries a median cost of two dollars. That contrasts sharply with the $12.72 charged by traditional banks and postal remittance operators.
This fee gap reflects an 84% reduction favoring cross-border workers. Such savings dismantle the claim that analog financial firms maintain justifiable monopolies anchored to unavoidable fixed operational expenses when moving purchasing power across international sovereign borders.
For decades, wire agencies defended elevated tariffs by citing correspondent banking layers. However, public ledger settlements replace cumbersome clearinghouses with programmable accounting protocols that operate continuously every day of the year without human authorization delays or administrative holidays.
This shift expands as surging cross-border transaction volumes accelerate the replacement of legacy settlement rails. In inflation-strained economies, capital seeks frictionless conduits capable of shielding family purchasing power against persistent local currency devaluation.
Tariff compression versus correspondent banking rents
Official figures from the World Bank database platform place the global average remittance cost at 6.36%. This toll frequently doubles across corridors in Sub-Saharan Africa, exceeding 8% on small retail consumer transfers.
High intermediation charges act as a regressive tariff on migrant labor. By settling balances across smart contracts, financial gatekeepers lose their pricing leverage to extract excessive margins merely for reconciling private database entries across disparate international borders.
In Latin America, dollar-pegged assets address urgent domestic realities. Recipient families no longer endure multi-day banking delays to access capital earmarked for urgent necessities such as food, primary healthcare, or regular household utility obligations.
Global targets outlined in the sustainable development goals framework mandated cutting worldwide remittance costs below 3% by 2030. Traditional financial infrastructure has consistently failed to meet this international milestone across vulnerable corridors for more than a decade.
By contrast, asset-backed digital tokens already achieve a median transfer cost of 1%. This structural pricing compression relies entirely on the programmatic efficiency of distributed accounting software rather than political pledges or corporate goodwill.
Nevertheless, capital flight toward foreign denominations alarms monetary authorities. When massive transaction flows bypass domestic institutions, economies confront an acute destabilizing liquidity outflow scenario that drains reserves and weakens local banking system deposits.
Physical reality and last mile settlement friction
Proponents of legacy money transmission insist that digital tokens cannot sustain families in cash-reliant developing economies. Their counter-argument emphasizes that recipients ultimately require physical notes to purchase local goods, rather than cryptographic token balances stored on mobile phones.
This operational critique remains entirely valid across developing communities. Local merchant networks rarely accept token payments, forcing users to convert balances via physical cash points that impose predatory foreign exchange spreads and local withdrawal commissions.
Empirical evidence documented in the Chainalysis global geography report confirms that adoption surges where informal commerce dominates. If off-ramps retain opaque fees, the initial 84% efficiency advantage evaporates before physical paper bills reach the recipient’s hands.
Restrictive domestic regulatory regimes further exacerbate terminal friction. Aggressive digital transaction taxes and cumbersome verification mandates frequently drive vulnerable households away from compliant settlement desks into volatile informal street markets where safety risks increase.
The cost advantage thesis would be refuted if physical cash off-ramps permanently capture all protocol savings through predatory spreads, or if central regulators entirely sever banking integration with authorized stablecoin liquidation desks.
If retail point-of-sale systems deploy seamless stablecoin acceptance over the next twenty-four months, paper currency dependencies will decline and the 84% cost savings will establish a permanent benchmark across cross-border settlement markets.
This article is for informational purposes only and does not constitute financial advice.