Today, cryptocurrencies are a legitimate and regulated industry. Just under a decade ago, no one could have imagined that the ecosystem would now feature licenses, exchange-traded vehicles, and institutional capital.
However, each of these victories came with a bill that many ignore. The dilemma is no longer whether cryptocurrencies will survive, but whether what we have today is still what was promised.
When Satoshi Nakamoto created Bitcoin in 2009, he did so with the vision of doing away with banks, asset managers, and states. Today, BlackRock sells BTC in an ETF, and Larry Fink calls it a “safe haven”. So, was it truly a victory?
From whitepaper to balance sheet asset
The first thing we lost was the narrative. Bitcoin went from being money free from government control to a store of value, only to later become a macro asset packaged for traditional portfolios.
Irrefutable proof of this lies in spot ETFs, which offer price exposure while preventing users from spending the asset or holding self-custody.
This is particularly striking in Ethereum. Companies like BitMine control roughly 5.6 million ETH, close to 4.7% of the circulating supply. When an asset lives on a corporate balance sheet, it becomes governed by the logic of dividends, institutional staking, and quarterly earnings reports.
What happened to decentralization?
The problem isn’t just narrative. It’s architectural. Foundry USA and AntPool control between 45% and 49% of Bitcoin’s hashrate and five pools account for over 80%.
Lido manages around 23% of all staked Ether. Together with Binance’s wBETH, it dominates about 88% of the liquid staking market. Meanwhile, Titan Builder produces approximately 52.6% of all blocks.
On top of this, staking yields dropped from over 5% in 2021 to between 2.4% and 2.7% in 2026. Running an independent validator node is no longer worth the trouble, making delegating this task to intermediaries the most logical choice.
Stablecoins: money with an off switch
This is one of the clearest signs. Circle froze around $109 million in USDC. Tether blocked nearly $550 million in USDT linked to sanctioned networks during 2026, destroying and reissuing a large portion of those frozen funds to law enforcement.
These companies shielded themselves under the argument that they were helping to “curb money laundering” and that recovering funds for victims is legitimate. But a digital dollar that can be frozen with a single click is not censorship-resistant money; it’s a double-edged sword that effectively turns into a bank dollar with better technology.
Code is no longer free expression
The hardest blow is judicial. Alexey Pertsev was sentenced to 64 months in prison in the Netherlands over the Tornado Cash case. In New York, Roman Storm was found guilty of conspiracy to operate an unlicensed money-transmitting business.
What makes all of this disturbing is the reasoning behind it: even though the smart contracts were immutable, maintaining an interface and relayers was interpreted as running a business.
In short, writing code remains legal, but keeping the front door open to a private protocol can be a crime. It is no surprise that parts of the DeFi ecosystem are shifting toward closed source—at the cost of auditability, as highlighted by the $5.8 million hack on Loopscale.
Not a death, but a fork
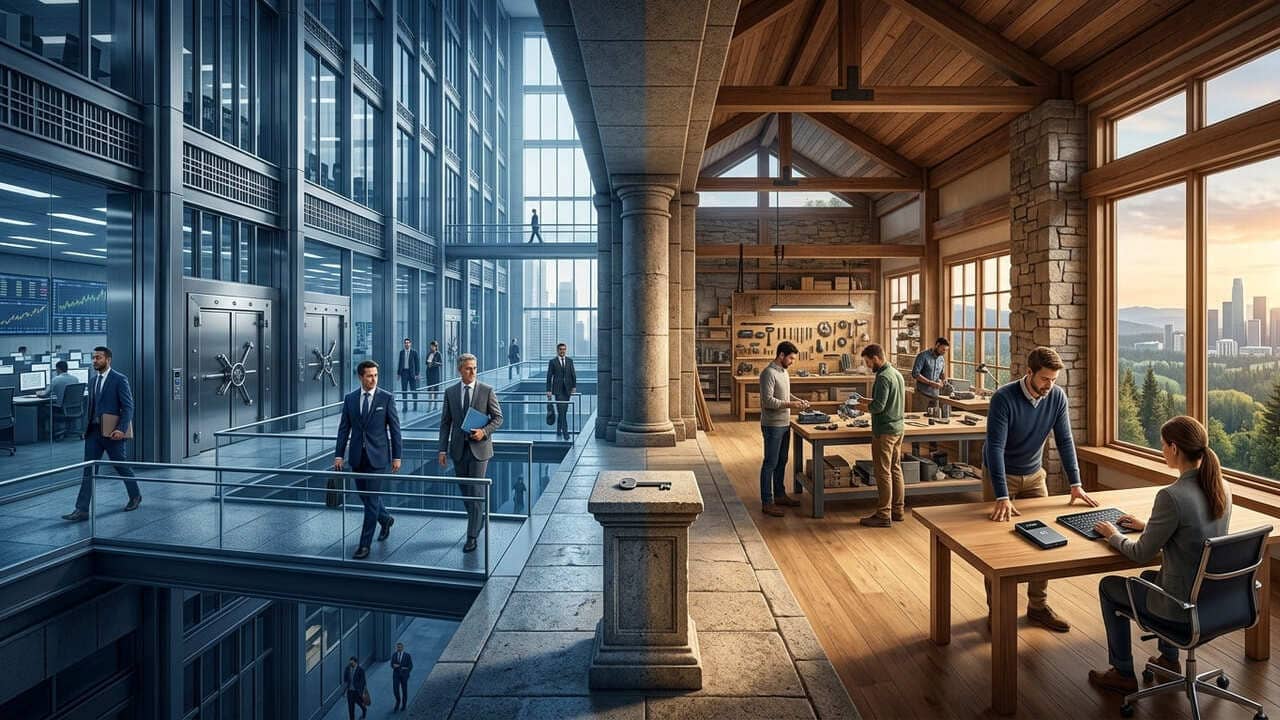
It might be overly dramatic to claim that crypto “sold its soul,” because there is something far more interesting going on beneath the surface: the market is splitting in two.
On one side, we have the institutional branch: ETFs, regulated stablecoins, KYC, and qualified custody. This segment holds the lion’s share of capital and provides liquidity, but it sacrifices privacy and sovereignty.
On the other side are the cypherpunks: permissionless networks, self-custody, personal nodes, and zero-knowledge cryptography. This space is smaller, legally exposed, and preserves the original mission.
There are signs of resistance. Vitalik Buterin is pushing to “Make Ethereum Cypherpunk Again,” and the Ethereum Foundation published a 38-page manifesto in March 2026 to reaffirm neutrality and privacy. Furthermore, censorship on MEV-Boost relays plummeted from 94.8% in 2022 to 18% in 2026. The culture is still alive, even if it no longer calls the shots.
Where does the risk lie?
The real risk isn’t that the institutional layer exists. It’s that it becomes the only visible version, leading users to mistake the Bitcoin logo for Bitcoin’s core purpose. If regulation turns licensing into a barrier to entry, the very middleman crypto aimed to eliminate returns under a different name: qualified custody, ETF fees, and validator commissions.