The latest CoinShares global investor study exposes a severe structural fracture across major economies: high-net-worth individuals are actively incorporating digital assets, while their wealth advisors remain tethered to outdated models. This divergence reshapes private wealth management across the United States, Britain, and Germany.
The long-standing characterization of these instruments as mere retail speculation is thoroughly contradicted by balance sheet reality. Understanding this fiduciary divorce is critical today because private capital moves with significantly higher technical velocity than the traditional intermediaries hired to steward it.
Hard data demonstrates an institutional transition in family balance sheets. Foundational assets such as Bitcoin now function as core strategic holdings, shedding their earlier identity as marginal experiments to establish themselves as quantitative liquid reserves accessible worldwide.
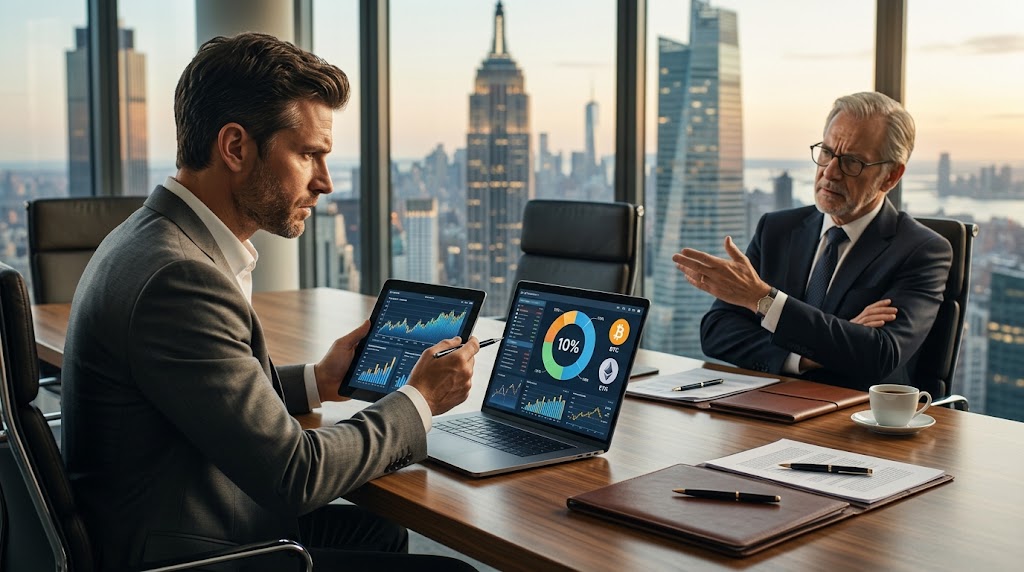
Survey findings reveal that affluent participants maintain an allocation close to ten percent of their liquid wealth in cryptoassets. This balance sheet weighting matches the exact capital commitments family offices traditionally deploy toward private equity partnerships and commercial real estate portfolios.
The primary driver behind this positioning is not short-term speculative trading. Affluent capital allocators pursue multi-year capital preservation, long-horizon compounding, and a defensive buffer against persistent purchasing power dilution across primary fiat reserve currencies.
Nearly ninety percent of these investors plan to increase their exposure over subsequent fiscal cycles. Crucially, they do not intend to utilize unregulated platforms, prioritizing institutional-grade custodians, transparent corporate governance, and regulated investment wrappers with comprehensive auditing standards.
Structural Realignment Across Private Portfolios
In earlier economic cycles, sophisticated wealth owners routinely spearheaded the adoption of alternative asset classes whenever sovereign debt yields degraded. Decades ago, venture capital partnerships and commodity futures underwent identical trajectories before achieving standardized acceptance across banking institutions.
Recent regulatory approval of spot funds accelerated this shift by dismantling administrative hurdles for institutional allocators. Liquid market pricing now reflects disciplined asset accumulation as wealth holders purchase audited shares rather than managing complex private cryptographic keys.
Skeptics maintain that structural volatility and uncertain tax treatments negate suitability for conservative portfolios. That counterpoint carries genuine validity given drawdown cycles exceeding fifty percent during macroeconomic liquidity contractions, which pose legitimate portfolio rebalancing and liquidity management challenges.
Furthermore, coordinated government intervention prohibiting commercial banks from providing digital asset custody would severely disrupt the thesis. Deprived of secure institutional rails and clear accounting guidance, asset allocations would revert to fragmented fringe environments unsuitable for fiduciary entities.
Yet macroeconomic forces push resolutely in the opposite direction. As outlined in the NIRS retirement asset insecurity report, escalating sovereign liabilities and structural currency debasement weaken confidence in conventional fixed income, compelling sophisticated capital to secure alternative reserve instruments beyond sovereign balance sheets.
The Operational Impasse Facing Wealth Managers
Despite compelling quantitative evidence, traditional wealth management remains remarkably stagnant. This widening gap stems not from client indifference, but from organizational inertia inside advisory firms that persist in applying obsolete risk paradigms to institutionalized digital asset products.
The resulting friction is unmistakable across daily advisory interactions. While ninety percent of affluent investors plan to expand allocations, they encounter stubborn skepticism from primary advisors regarding how to structure digital exposure within broader wealth preservation strategies.
Indeed, four in ten financial advisors actively resist onboarding digital assets or lack baseline technical literacy regarding their integration. This advisory deficit creates sharp misalignment between modern wealth owner requirements and existing wealth management capabilities.
Advisory practices frequently cite internal compliance hurdles or outdated administrative policies to justify reluctance. However, defensive conservatism overlooks that private clients are bypassing traditional intermediaries altogether, deploying capital directly through specialized institutional platforms offering compliant execution.
The loss of fiduciary relevance is the direct operational cost of this professional complacency. High-net-worth investors do not wait for permission from conservative wealth managers; they allocate substantial balances toward modern custodians equipped with sophisticated digital infrastructure.
The CFA Institute technical research documents that institutional education deficits form the primary barrier across asset management practices. Portfolio practitioners failing to integrate multi-asset risk modeling remain incapable of addressing sophisticated capital allocation inquiries.
Modernizing investment committees has become an operational requirement for legacy private wealth institutions. Advisors failing to incorporate regulated digital products will encounter client attrition toward digital-native financial platforms providing comprehensive institutional custody.
Global private banking must recognize that digital asset demand is no longer driven by promotional speculative fever. It represents deliberate positioning by sophisticated clients deploying significant capital for portfolio diversification and systemic currency risk hedging.
Firms that proactively upgrade their technical infrastructure will capture enduring private client relationships over the coming decade. Conversely, advisors clinging to outdated dogmas will see advisory market share steadily erode toward nimble market competitors.
If affluent investor allocations maintain ten percent portfolio weightings and regulators protect institutional custodial gateways, advisory refusal rates will drop below twenty percent before 2028 to prevent substantial capital migration toward tech-enabled competitors.
This article is for informational purposes and does not constitute financial advice.