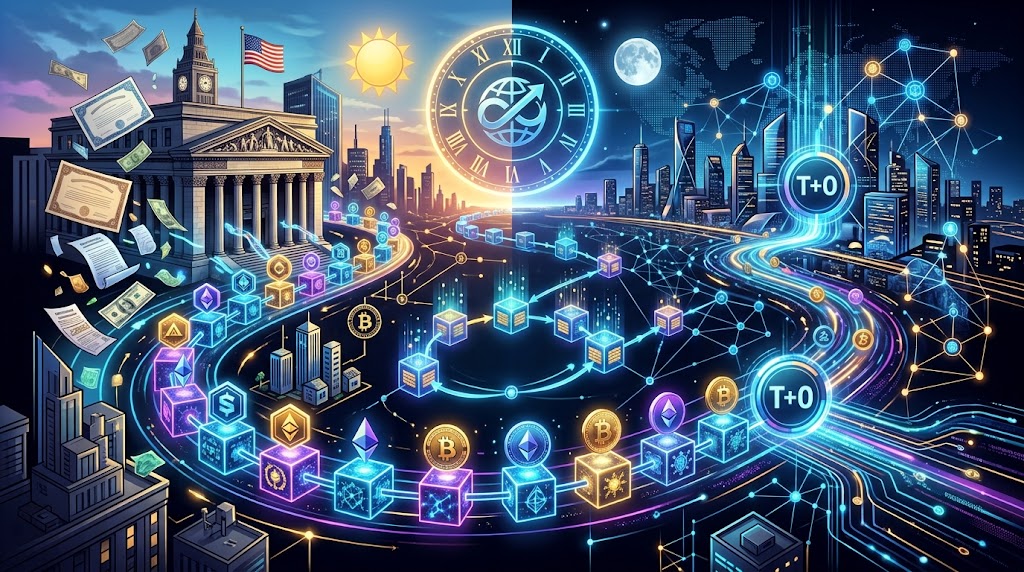
CoinFund President and Managing Partner Chris Perkins detailed his analysis on financial infrastructure during a Tokenization Talks session. Perkins stated that the arrival of continuous 24/7 markets will unfold gradually before consolidating into a sudden, comprehensive transformation across global financial venues.
24/7 markets are here. It will be slowly then all at once. @perkinscr97 explains on Tokenization Talks with @haumicharts. pic.twitter.com/UlI6cJRxGx
— Franklin Templeton Digital Assets (@FTDA_US) September 25, 2026
Conventional exchange architecture still relies on twentieth-century operating hours, restricting asset matching and settlement to weekdays and domestic banking schedules. In contrast, distributed ledger infrastructure enables continuous transaction processing during weekends and official bank holidays without system interruption.
The underlying thesis argues that structural adoption will progress non-linearly. Institutional participants initially deploy specific tokenized products in ring-fenced pilot environments before modifying clearinghouse frameworks, which manage trillions of dollars in market liquidity under established deferred-net settlement cycles.
During this initial phase, legacy clearing systems operate in parallel with blockchain networks. This hybrid setup allows risk managers to evaluate automated smart contracts without dismantling existing legal arrangements that govern primary debt and equity registries.
Operational clearing friction and atomic settlement
In traditional fixed income and foreign exchange markets, standard T+1 and T+2 settlement cycles create persistent bilateral settlement risk across disconnected time zones. Atomic clearing on distributed ledgers eliminates this temporal counterparty exposure through simultaneous exchange of cash and tokenized securities.
Nevertheless, continuous trading generates distinct liquidity management requirements. Financial institutions must maintain adequate liquid reserves to back real-time settlements during windows when wholesale central bank payment rails, such as Fedwire or Target2, suspend operations for standard weekend maintenance.
This operational constraint accelerates the adoption of on-chain cash equivalents. Tokenized money market funds and fully reserved stablecoins provide functional collateral buffers, enabling uninterrupted funding flows between institutional participants when interbank payment windows remain closed.
Collateral management and debt market tokenization
Sovereign debt represents one of the fastest growing segments for digital representation. Major asset managers have tokenized short-term United States Treasury obligations, establishing these instruments as viable real-time collateral transfer assets between qualified institutional dealers and liquidity providers.
In repurchase agreement (repo) markets, locking capital across weekends inflates short-term financing costs. Tokenization reduces balance sheet drag by allowing counterparties to mobilize digital collateral and adjust margin balances in seconds rather than waiting for traditional opening hours.
Perkins emphasized that technical capability does not supersede regulatory standards. Regulatory capital requirements, automated compliance checks, and auditable network controls remain mandatory conditions for any regulated firm seeking to trade or settle on-chain assets under official supervisory oversight.
Current institutional implementations concentrate on permissioned ledgers with controlled governance. Banking consortia are testing continuous matching engines capable of synchronizing cryptographic accounting records while maintaining compliance with domestic regulatory reporting rules and international capital mandates.
Network dynamics and liquidity consolidation
The concept of gradual progress culminating in rapid market concentration reflects financial network dynamics. As liquidity migrates between legacy clearinghouses and continuous trading rails, institutional order volume naturally aggregates toward venues providing superior uninterrupted operating liquidity.
When a critical threshold of global custodians adopts continuous settlement, primary exchanges will encounter commercial pressure to prolong their operating hours. Trading firms operating under restricted daily sessions face pricing disadvantages against platforms that maintain 24-hour liquidity.
Several administrative and legal challenges remain before full industry convergence. Standardized protocols for handling corporate actions, such as stock splits, bond coupon payments, and dividend record dates over non-business days, still lack uniform regulatory approval across primary jurisdictions.
The verifiable progress point rests on forthcoming policy frameworks and clearing guidance that regulatory authorities in the United States and the European Union plan to issue regarding institutional digital custody and settlement.
This article is for informational purposes only and does not constitute financial advice.