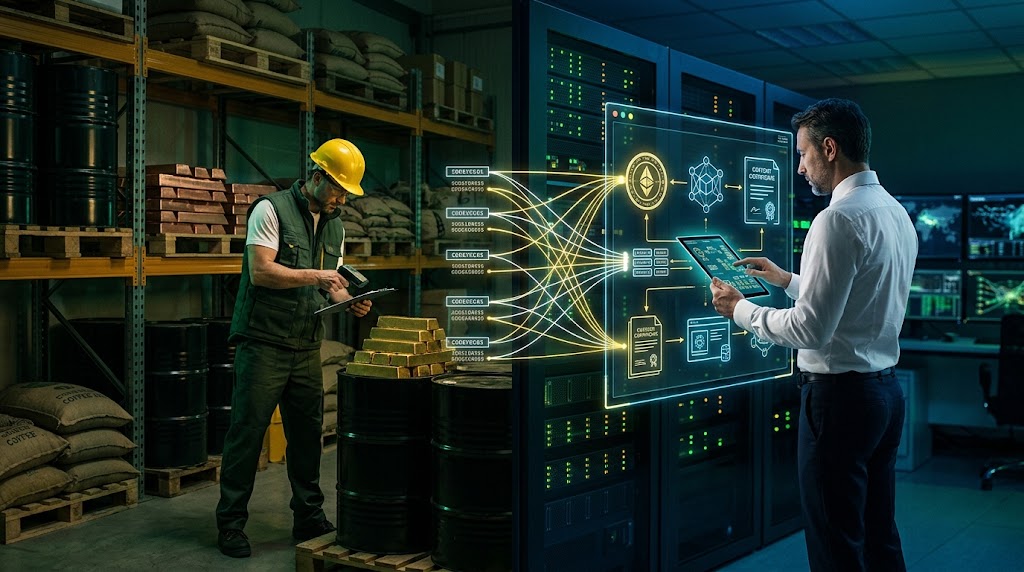
Raw commodity digitalization currently faces a fundamental legal contradiction between cryptographic ledgers and property rights. According to a World Gold Council research report, the market capitalization of tokenized gold products exceeded four billion dollars by 2025, demonstrating accelerating institutional interest in alternative digital representations of physical collateral.
However, this widespread capital influx confuses distributed accounting entries with true physical asset ownership. Token holders do not possess tangible bullion, but rather an unsecured or custodial contractual claim against the issuing legal entity.
The boundary between property rights and personal credit claims defines this operational reality. Under established commercial and civil legal traditions, ownership of physical property demands direct possessory control, whereas automated smart contracts merely execute record transfers across closed cryptographic registries governed by state corporate law.
When a trader transfers an on-chain token, no physical ounce moves within vaults located in London or Zurich. What actually circulates across public networks is a tokenized receipt dependent upon traditional institutional intermediaries.
Legal architecture: depository receipts versus smart contract code
Corporate structures behind prominent issuers demonstrate this institutional reliance. According to the official PAX Gold whitepaper document, each digital token corresponds to one fine troy ounce held at Brink’s vaults in London, yet underlying title remains governed exclusively by the custodial trust framework of New York State banking regulations.
Consequently, the token holder holds a contractual claim against a regulated financial intermediary rather than unfettered dominion over allocated bars. Should the issuer freeze the smart contract address, material redemptions cease completely.
This structural dynamic mirrors seventeenth-century London goldsmith practices. Those early craftsmen issued paper deposit receipts representing gold stored in secure vaults, notes that soon circulated as representative bearer instruments long before the formal inception of modern sovereign central banking institutions.
Similarly, London Metal Exchange warehouse warrants served as negotiable physical commodity claims for decades. Whenever physical convertibility encounters severe operational friction, as occurred in 1971 under Bretton Woods, paper representations inevitably decouple from real collateral.
Despite these persistent structural frictions, the broader tokenized gold market expansion trend has achieved continuous secondary market liquidity that paper warrants never matched, enabling global around-the-clock decentralized trading without requiring immediate physical vault settlements between counterparties across diverse international financial jurisdictions.
Yet continuous liquidity masks acute temporal asymmetry. While blockchain tokens change ownership in seconds, taking physical delivery of an underlying gold bar requires complex audits, armored transport, and high redemption fees.
Issuers like Tether Gold and Paxos establish significant minimum thresholds for physical withdrawals. Demanding redemptions equal to full London Good Delivery bars of roughly four hundred troy ounces effectively precludes ordinary retail token holders from ever taking physical custody of the underlying metal.
For retail investors, the token operates as a synthetic price tracker. It mirrors international commodity benchmark prices efficiently, yet remains divorced from direct possession inside the user’s private physical perimeter.
Doctrinal counterpoints and cross-border property rights
International legal frameworks explicitly confirm this division between tokens and physical collateral. The binding UNIDROIT digital assets principles establish that cryptographic control over a digital token does not automatically confer proprietary ownership over linked real-world assets without explicit national statutory recognition.
Under these private international law standards, physical warehouse jurisdiction governs proprietary disputes. This reality directly nullifies assertions that decentralized blockchain smart contracts possess jurisdictional autonomy over off-chain tangible commodities.
Proponents of asset tokenization present a counterargument centered on operational efficiency and institutional segregation. They argue that bankruptcy-remote special purpose trusts legally isolate physical reserves from issuer insolvency, ensuring that circulating tokens represent strictly audited, allocated bars protected from general creditor claims.
For hedge funds and family offices, this legal ring-fencing provides adequate security under regular market conditions, offering exposure without the cumbersome expense of leasing private vaults or arranging independent physical security logistics.
A clear parallel emerges when analyzing tokenized real estate collateral yields within private property markets. In both domains, performance and ultimate asset recovery depend on legal entity design rather than smart contract execution, anchoring digital tokens to local judicial systems and statutory corporate governance.
This thesis would be invalidated if commercial codes globally recognize commodity tokens as electronic documents of title conferring direct property rights, enabling summary enforcement against custodians without requiring intermediary judicial intervention.
Until such statutory harmonization materializes, geopolitical risk remains concentrated in centralized physical vault hubs. Regulatory mandates, cross-border asset freezes, and statutory court orders can compel token issuers to utilize smart contract pause mechanisms, halting secondary market transfers instantaneously across international borders.
Unlike allocated gold kept in private safe-deposit boxes, tokenized bullion never leaves domestic sovereign court jurisdiction. Digital token holders enjoy unprecedented transactional speed, yet trade away unconditional proprietary sovereignty.
Ultimately, recognizing that physical custody dictates token solvency brings this technological innovation back to classical corporate banking realities. Distributed ledgers dramatically streamline fractional secondary accounting, but blockchain records cannot convert an intermediated contractual promise into unconditional physical possession of raw commodities.
If an institutional vault custodian encounters formal legal insolvency proceedings, the secondary market discount on the associated commodity token will exceed three percent against physical spot bullion within thirty days.
This article is for informational purposes and does not constitute financial advice.