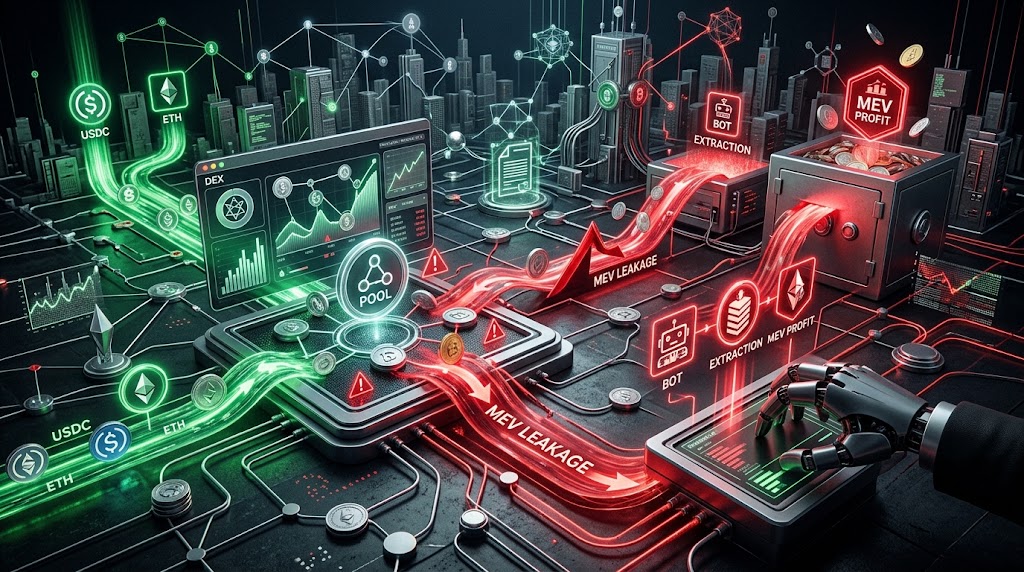
Maximal extractable value no longer represents merely a technical byproduct of blockchain transaction sequencing. In contemporary decentralized finance, it constitutes a structural leakage of economic value that systematically transfers organic capital from passive liquidity providers toward automated arbitrage searchers and block validators.
This dynamic demands immediate scrutiny because decentralized trading architectures operate with compressed margins. Millions of dollars vanish annually through cross-venue price discrepancies that applications generate internally yet fail to capture for their core participants.
Formal market microstructure research initiated by Philip Daian in 2019 first exposed this systemic drain. His foundational paper documented automated trading bots aggressively competing through priority gas auctions, unleashing toxic arbitrage against user deposits housed in smart contracts before private transaction ordering channels existed.
Empirical extraction data from Flashbots indicates that searchers have extracted over 1.4 billion dollars on Ethereum since 2020. This volume originated predominantly from forced collateral liquidations and sandwich attacks on unsuspecting retail swap orders.
The root structural flaw stems from how consensus mechanisms process state changes without evaluating liquidity health. While block builders receive direct bribes to reorder transactions profitably, passive capital providers bear the entire unhedged burden of adverse selection.
Adverse arbitrage and yield erosion in liquidity pools
Understanding this hidden erosion requires analyzing the baseline of economic security in decentralized finance. The resilience of an exchange protocol does not depend solely on audited smart contracts, but on its capacity to retain surplus value against predatory external incentives.
Verifiable fact: automated market makers adjust internal pricing curves only when an external party submits a transaction. Analytical interpretation: this inherent latency transforms external market movements into one-way value extractions, unintentionally subsidized by protocol trading fees.
Researchers from Columbia University and Stanford formalized this structural dynamic in August 2022 by introducing the Loss Versus Rebalancing framework. This mathematical metric separates general market volatility from the specific loss suffered against informed latency traders.
The study by Milionis, Moallemi, Roughgarden, and Zhang proved that passive constant-product liquidity pools experience a systematic loss versus rebalancing cost model. Across major liquid trading pairs on Ethereum, this adverse selection cost devoured 50% to 70% of gross fee revenue.
Decentralized exchanges originally operated in 2018 under the assumption that trading volume fees would offset market swings. The widespread deployment of uncollateralized flash loans in 2020 eradicated capital constraints for arbitrageurs, turning fleeting price discrepancies into instant, risk-free balance extractions.
Decentralized treasuries frequently mask this ongoing bleed through aggressive native token emissions. By artificially bolstering headline yields with dilutive governance tokens, protocols conceal that their underlying commercial cash flow is almost entirely diverted to non-aligned infrastructure operators.
Market efficiency trade-offs and internal value recapture
Modern multi-chain rollups complicate the execution landscape by dispersing capital across disparate settlement environments. Severe liquidity fragmentation across decentralized venues widens cross-chain arbitrage spreads, offering lucrative routing profits to private searchers while degrading price execution quality for regular traders.
An opposing perspective grounded in quantitative finance views this extraction differently. Proponents argue that continuous arbitrage provides an essential service by aligning decentralized spot rates with centralized order-book venues, thereby preventing stale pricing across the broader market.
This counterpoint carries operational validity in specific applications. On decentralized lending platforms, automated liquidation bots rapidly seize undercollateralized debt during steep market downturns. Without competitive incentives for liquidators, protocols would accumulate catastrophic bad debt, threatening systemic solvency.
The premise that MEV represents uncaptured protocol revenue would be invalidated if internal capture mechanisms introduce unacceptable execution drag. If order-flow auctions cause unacceptable trade delays or deter institutional retail flow, the resulting loss in trading fees would surpass any captured arbitrage yield.
Protocol architects are nonetheless building native defenses to reclaim value. Batch-auction exchanges such as CoW Swap utilize uniform clearing prices to eliminate sandwich attacks, ensuring transactions settle without leaking priority ordering premiums to external searchers.
Similarly, newer decentralized exchange designs introduce modular hooks explicitly aimed at minimizing the redirecting fees toward block validators. These hooks allow liquidity pools to auction the first swap right of each block, returning the arbitrage margin directly to active liquidity providers.
The overarching challenge is fundamentally distributive rather than technical. If governance frameworks treat extractable value as organic protocol earnings, decentralized applications will prioritize architectures that penalize predatory front-running and protect the capital base of their liquidity providers.
If automated liquidity pools deploy internal pre-trade auctions that capture at least 40% of latency arbitrage, the net annualized yield for passive market makers will consistently exceed benchmark staking yields across paired assets.
Testing this relationship will require comparing net return metrics before and after the introduction of internal auction hooks, isolating broader market volatility through auditable on-chain datasets over multi-month observation cycles.
Until decentralized finance directly internalizes these transaction flows, protocols will continue leaking their most valuable economic product to outside intermediaries, forfeiting sustainable revenue streams that belong to their own stakeholders.
This article is for informational purposes and does not constitute financial advice