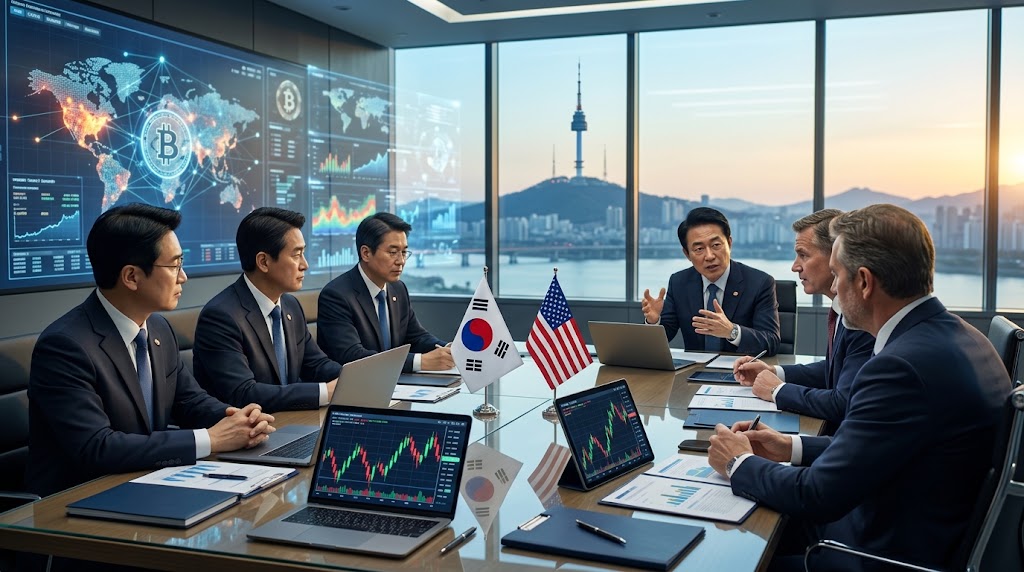
South Korean authorities proposed a fourth two-year tax delay on capital gains derived from virtual asset transactions. The measure seeks to shift the statutory enforcement date from January 2027 to January 2029.
Finance Minister Lee Hyoung-il announced the plan on November 5, 2026, stating that the government will coordinate legislative adjustments with the National Assembly. The decision reverses the ministry’s position maintained throughout early 2026, which favored an immediate 2027 implementation.
The tax design establishes a combined levy of 22%, comprising a 20% national capital gains tax and a 2% local income surcharge. This duty applies solely to annual net profits surpassing the statutory allowance of 2.5 million won, roughly 1,860 dollars.
South Korea initially scheduled this taxation framework for January 2022. Successive legislative amendments postponed the date to 2023, 2025, and 2027, driven by market readiness concerns and investor pushback across consecutive parliamentary sessions.
The executive outlined its justification through an official Ministry of Finance document. Officials highlighted that bilateral tax reporting under the OECD Crypto-Asset Reporting Framework (CARF) with the United States will not activate until 2029.
Enforcing capital gains taxes without active cross-border data exchanges could disadvantage domestic crypto exchanges relative to overseas platforms. The ministry stressed that unilateral local enforcement risks capital flight and creates asymmetric information gaps for tax authorities.
The updated plan incorporates a statutory provision allowing deductions for net capital losses against trading gains over three subsequent tax years. This concession addresses criticism from retail investors who previously faced taxes on single profitable years despite aggregate portfolio losses.
Domestic exchanges and financial firms have sought regulatory clarity for institutional infrastructure and on-chain settlements. The shift occurs alongside private sector testing for digital transaction tooling, such as recent domestic initiatives to test institutional stablecoin payment settlements.
The government plans to submit statutory revisions to the National Assembly during the 2027 regular session. Technical calculation manuals and compliance guidelines for virtual asset service providers will follow in the first half of 2028.
Regulatory oversight across digital asset holdings continues to tighten ahead of tax enforcement. Authorities have simultaneously moved to enforce strict disclosure rules where regulators require reporting crypto holdings for online promoters and key market influencers.
The proposed tax timeline remains subject to National Assembly committee review and legislative approval scheduled for 2027.
This article is for informational purposes only and does not constitute financial advice.