The official announcement regarding the closure of Binance Pool signals the platform’s complete departure from direct network infrastructure. After six years in operation, the decommissioning of its Stratum servers is not merely an internal routine adjustment. It reflects a decisive strategic pivot across corporate digital asset firms.
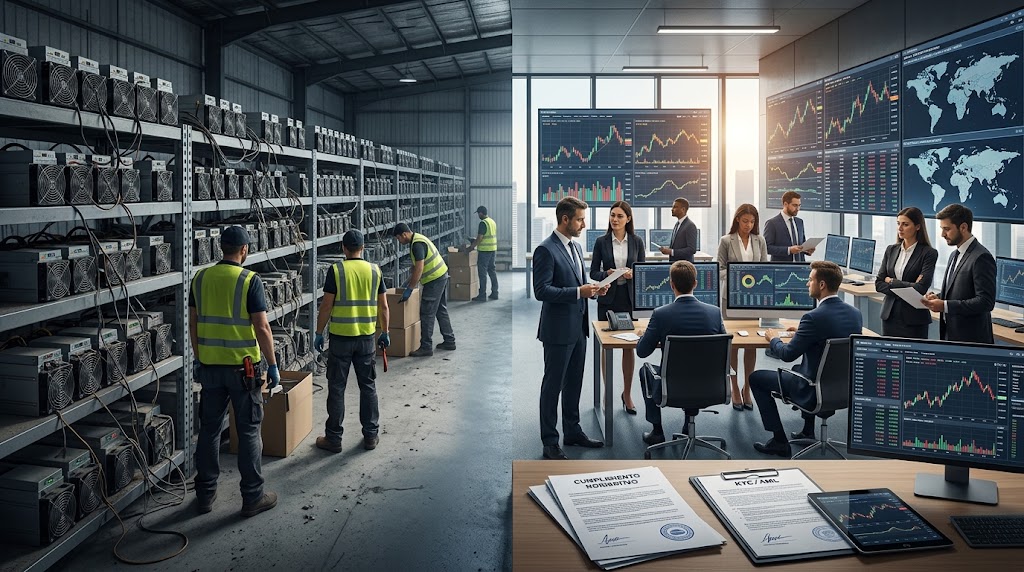
The initial thesis behind running mining pools was vertical integration: capturing raw liquidity directly at issuance. However, that technical calculation now faces severe margin compression across all business lines. Managing mining pools demands continuous infrastructure maintenance, immediate liquidity for payout settlements, and operational overhead that yields minimal returns compared to derivatives trading.
Industrial-scale proof-of-work mining now operates under razor-thin margins. Official estimates published by the U.S. Energy Information Administration reveal that cryptocurrency mining accounts for between 0.6% and 2.3% of total domestic electricity demand. Such heavy capital intensity quickly sidelines multi-service intermediaries that do not operate proprietary physical facilities.
Data compiled by the Cambridge Bitcoin Electricity Consumption Index tracks global annual demand consistently above 130 TWh. For an exchange maintaining less than 3% of global network hash rate, sustaining specialized pool architecture creates legal friction and technical risks that dwarf net operating revenue.
Historically, trading platforms launched mining divisions to lock in primary block rewards and funnel supply into their order books. Before the 2021 market maturation, controlling hashing power established brand authority and secured organic customer deposits across multiple continents.
That commercial dynamic has largely disappeared. Successive block subsidy halvings accelerated corporate consolidation into dedicated facilities that handle capital via specialized over-the-counter agreements. Consequently, consumer-facing mining pools hosted by trading platforms lost their original strategic utility.
The foundational principles outlined in the original Bitcoin whitepaper envisioned security driven by distributed computation, where participants respond directly to protocol incentives. When centralized platforms attempted to incorporate that technical layer, they burdened core operations with non-essential industrial dependencies.
Modern exchanges now concentrate capital allocation on regulated custody, derivatives settlement, and compliance systems. This trajectory aligns digital asset firms with traditional financial brokerages, severing ties with technical block generation.
Hashrate Distribution and the Institutional Counterpoint
An optimistic argument contends that the departure of centralized exchanges benefits decentralized consensus. With Binance disabling its endpoints, independent hashing power must disperse toward alternative mining collectives, limiting the aggregation of network authority within major centralized exchange entities.
Nonetheless, a compelling counterpoint challenges that outcome. Severing auxiliary pools does not inevitably foster an open network architecture. Most displaced hashing power historically migrates toward dominant mining consortiums, inadvertently reinforcing hash concentration among a handful of North American and Asian institutional operators.
This counterpoint would be disproven if redirected miners broadly adopt protocols that enable autonomous block template selection, such as Stratum V2 implementations. If independent hash producers decentralize template creation, the corporate retreat will have undeniably strengthened censorship resistance.
Stricter global oversight has simultaneously raised the cost of coordinating public mining servers. Running open pools exposes exchanges to liability regarding transaction inclusion, counter to the rigorous filtering expected of licensed entities.
Within a mature economic landscape, corporate margins favor pure financial facilitation over physical verification. Coordinating external hashing hardware introduces complex operational vulnerabilities that no longer serve exchange balance sheets.
The structural separation of financial speculation from industrial verification marks a decisive transition. Technical consensus and financial intermediation now run on distinct commercial rails across Bitcoin.
If transaction fees continue to represent less than 15% of aggregate block rewards over subsequent quarters, public pool hosting will permanently consolidate into specialized energy infrastructure operators, cementing the exit of digital asset exchanges from physical consensus mechanisms across the broader Mercado.
This article is for informational purposes only and does not constitute financial advice.