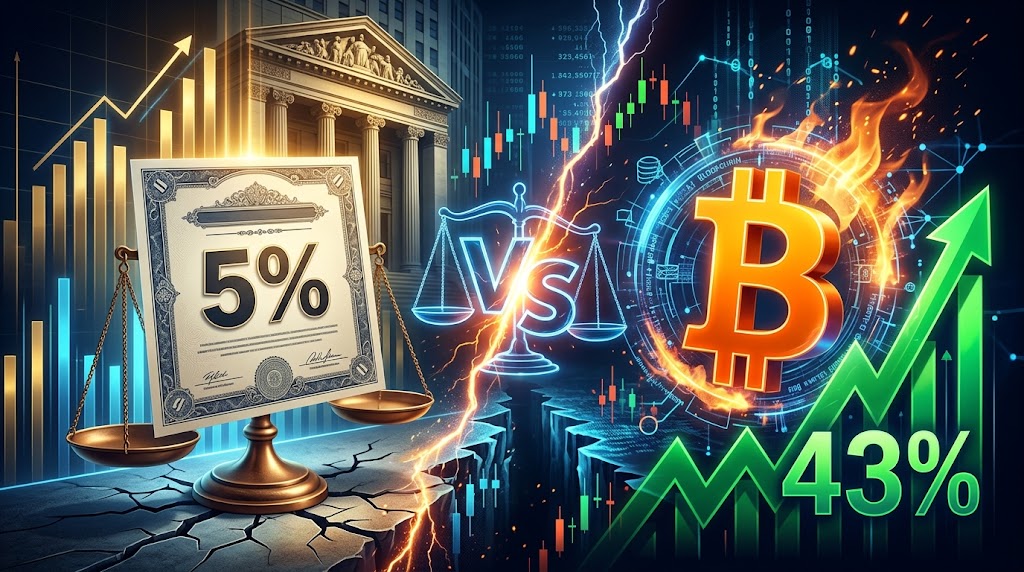
The 43% rally recorded by Bitcoin during the third quarter faces severe global monetary tightening headwinds. While institutional capital sought exposure following the approved SEC official statement, the United States 10-year Treasury yield climbed past 5.2%.
This divergence frames an essential macroeconomic dilemma. Non-yielding assets historically struggle when benchmark sovereign paper offers risk-free nominal returns above 5%, a dynamic absent from global financial markets for over a decade and a half.
Global liquidity conditions dictate returns across alternative assets. The restrictive interest rate trajectory pursued by the Federal Reserve aims to suppress inflation persistence, actively draining speculative excess through ongoing balance sheet quantitative tightening measures.
Historical precedent highlights this shift: the 2017 expansion unfolded within an ultra-loose regime marked by near-zero rates and expansive central bank balance sheets. Today, financial conditions reflect the steepest cost of capital documented since 2008.
Restrictive rates versus traditional capital opportunity cost
When government debt yields 5.2%, institutional asset managers confront a steep hurdle rate before deploying capital into volatile structures. The recent US Treasury refunding statement outlines unprecedented issuance volumes required to fund persistent federal budget deficits.
When real risk-free yields outpace baseline consumer price inflation, economic incentives to allocate toward non-cash-flow assets contract significantly. Concurrently, declining broad money growth limits the net liquidity required to sustain prolonged speculative asset rallies.
Under orthodox monetary theory, the recent quarterly surge could represent a transitory bull trap. Compressed risk premiums historically precede sharp downside valuations whenever benchmark bond yields stay elevated for an extended duration.
Conversely, an alternative interpretation argues that rising long-end yields do not reflect real economic dynamism. Bond market specialists contend that surging term premiums instead signal investor skepticism regarding long-term fiscal solvency and debt issuance overload.
Fiscal expansion fuels sovereign debasement dynamics
Unprecedented federal debt accumulation undermines structural confidence in fiat stability. As detailed in the CBO budget and economic outlook, net mandatory interest outlays now surpass major discretionary expenditure categories within the federal budget.
Under this framework, institutional capital anticipates that elevated debt servicing costs will eventually force central banks into balance sheet re-expansion. The monetary debasement trade gains traction as an explicit hedge against the long-term dilution of fiat currency purchasing power.
Participants embracing this thesis treat algorithmic digital scarcity as a structural shelter against debt monetization. To these allocators, the 43% quarterly rally reflects preemptive repositioning against sovereign balance sheet deterioration rather than ungrounded speculative euphoria.
This counter-thesis would face invalidation if federal authorities implement credible fiscal consolidation while the central bank orchestrates a sustained disinflation without introducing emergency liquidity backstops or renewed asset purchase facilities.
If the 10-year Treasury yield sustains above 5% alongside robust foreign auction demand without central bank intervention, high opportunity costs will cap structural liquidity inflows into non-yielding assets; if debt-servicing friction forces monetary accommodation within twelve months, capital flows toward scarce assets will validate the currency debasement hypothesis.
This article is for informational purposes only and does not constitute financial advice.