The legislative push to establish statutory certainty for digital assets across the United States has triggered an acute constitutional confrontation. Framed as necessary market modernization, the proposed bill threatens to strip fundamental judicial protections away from everyday citizens navigating complex predatory fraud.
Congressional proponents argue that single-portal federal oversight creates regulatory efficiency and accelerates domestic adoption. However, Washington’s administrative acceleration sidelines frontline state prosecutors at the exact moment criminal syndicate extraction reaches historic financial peaks.
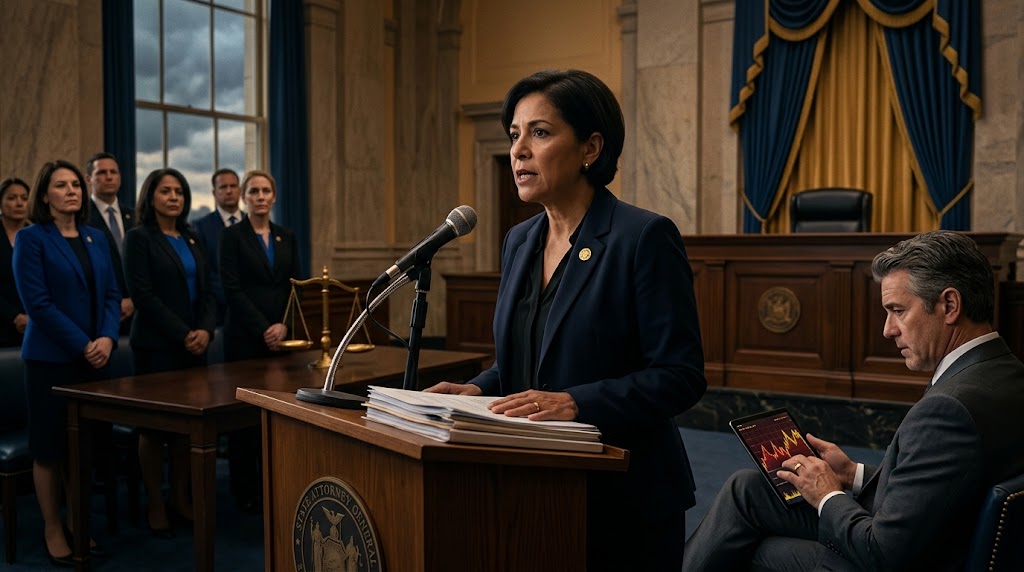
On September 14, 2026, an 18-state coalition delivered a formal Senate petition opposing the pending draft. Attorneys general from key jurisdictions warned that preempting state oversight eliminates the primary enforcement line defending consumers from digital fraud.
Federal data demonstrates the magnitude of the underlying crisis. The FBI documented $11.4 billion in cryptocurrency fraud complaints throughout 2025, representing a 22% annual surge where individual losses averaged more than $62,000 per victim.
Complementary reporting from the Federal Trade Commission confirmed $1.78 billion in direct payment losses in 2025. Concurrently, data analytics firm TRM Labs logged a historic illicit volume estimate of $158 billion across illicit addresses during 2025, marking an annual climb of 145%.
These statutory pressures reflect prior warnings surfaced when Senator Kevin Cramer pushes legislation forward under rigid timelines, often placing speedy floor debate ahead of enduring state enforcement prerogatives.
Bipartisan compromise emerged primarily through high-profile executive ethics arrangements. As detailed by Associated Press investigative reporting, Donald Trump agreed to divestment and blind trust requirements regarding personal commercial interests to secure pivotal Senate votes ahead of final passage.
Yet reconciling executive conflicts of interest does not remedy institutional vulnerability for defrauded citizens. Swapping presidential ethics restrictions for statutory language that curbs local prosecutors represents an asymmetrical concession detrimental to public law enforcement.
The erosion of historic state Blue Sky authority
State-level securities oversight originated more than a century ago as a vital bulwark against exploitative issuers. Kansas enacted the first statute in 1911, codifying the doctrine that regional proximities yield faster restitutions for retail investors.
When Congress passed the Securities Act of 1933, Section 18 carefully codified cooperative federalism principles. Federal registration was designed as a national baseline, explicitly retaining state authority to prosecute deceptive practices and unlicensed local promoters.
The current federal framework jeopardizes this dual structure through sweeping preemption mechanisms. Prosecutors point out that expansive “qualified transaction” exceptions would effectively eliminate state registration mandates, creating legal ambiguity that exploitative operators will systematically exploit during trial proceedings.
State intervention records reveal the structural reliance on local regulators. Enforcement registries compiled by the state securities coalition NASAA show more than 330 formal enforcement proceedings launched against crypto scam networks since 2017 alone.
Opponents of decentralized state oversight counter that navigating fifty distinct state standards introduces prohibitive compliance overhead. Industry trade groups maintain that uniform federal standards are essential to preserve domestic competitiveness and eliminate regulatory forum shopping.
This friction captures the central dilemma explored in the CLARITY Act ultimatum, where uniform technical definitions risk transforming dynamic market innovation into an ecosystem administered by federal bureaucratic discretion.
The consolidation argument falters on agency operational capacity. Federal watchdogs invariably allocate investigative resources toward systemic corporate institutions, routinely leaving micro-cap token rug pulls and syndicated consumer schemes entirely unaddressed.
The argument favoring exclusive federal preemption would lose validity if explicit state anti-fraud powers remain intact while registered digital asset exchanges sustain capital formation and liquidity without regulatory paralysis.
If federal preemption clauses pass without broad enforcement carve-outs, procedural delays and jurisdictional litigation will depress victim restitution rates across regional state courts over the next two fiscal years.
This article is for informational purposes only and does not constitute financial advice.