Corporate attempts to veto synthetic claims built on public shares challenge fundamental principles of market fungibility. Under the Delaware corporate statutory legal framework, an issuer creates capital stock but does not possess an inherent monopoly over third-party derivative instruments engineered to reflect the market value of those freely transferable securities.
This jurisdictional conflict accelerated following the public clash between Robinhood chief executive officer Vlad Tenev and AMC Entertainment leadership in September 2026. Tenev argued that public corporations should not hold veto power over financial products that leave the official stock ledger, corporate duties, and shareholder voting rights completely unaltered.
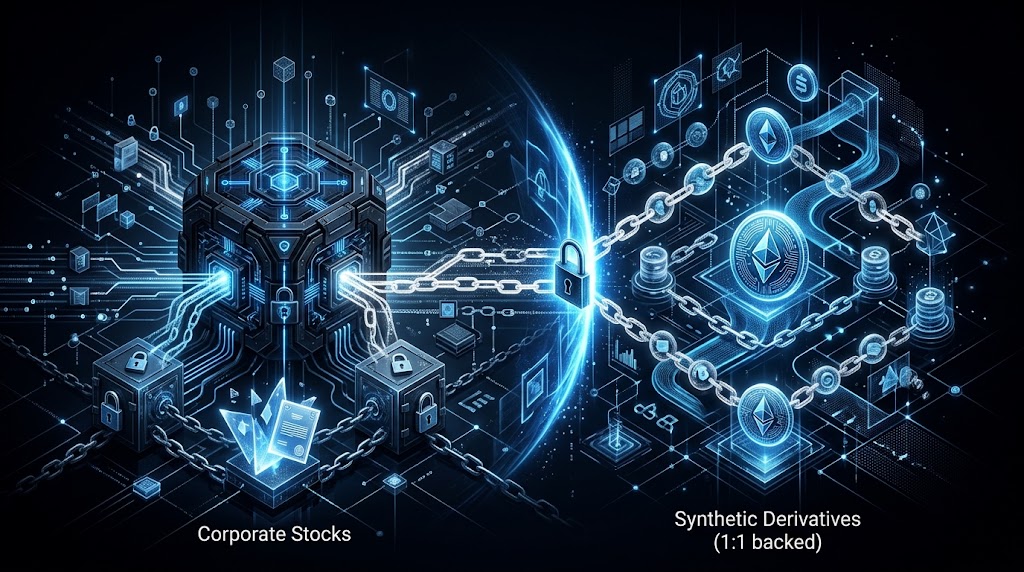
The operational architecture deployed across international markets relies on offshore subsidiaries like Robinhood Assets Jersey Limited. This entity purchases underlying domestic equities held with licensed custodians, issuing corresponding digital receipts on a one-to-one basis. Holders obtain purely synthetic economic exposure without acquiring voting representation or direct rights at annual meetings.
For expanding crypto companies, structuring these synthetic certificates represents a natural modernization of retail brokerage services. Intermediaries purchase equity legally in liquid markets and package economic exposure for foreign retail investors who otherwise face prohibitive geographic, tax, or banking barriers to accessing primary United States national securities exchanges.
Granting corporate boards veto authority over secondary financial instruments would grant executives unprecedented control over private property. An equity investor purchases legal title that can be pledged, deposited, or referenced in bilateral derivative contracts under prevailing commercial codes without soliciting discretionary permission from the original issuing company.
Securities history firmly supports this open market precedent through unsponsored depositary receipt programs. As detailed in the official bulletin on American depositary receipts, major banks historically established cross-border trading facilities without the cooperation or consent of foreign issuers, responding directly to domestic demand for accessible foreign equity exposure.
The same legal rationale underpins listed equity options traded on venues like the Chicago Board Options Exchange since 1973. Publicly listed companies do not possess veto rights over standardized put and call contracts referencing their common stock, even though options trading directly influences underlying share price volatility.
Similarly, the first-sale doctrine and unlisted trading privileges establish that once securities enter public circulation, issuers cannot micromanage secondary market activity. Preventing intermediaries from packaging exposure to freely transferable shares would disrupt capital formation and grant management teams arbitrary power over secondary liquidity channels.
Recording token balances using distributed blockchain networks does not alter the fundamental economic reality of the underlying financial instrument. Using smart contracts to automate settlement and balance tracking merely substitutes legacy ledger technologies, rather than creating a novel legal category requiring affirmative corporate licensing.
Tenev’s central argument captures this operational reality: moving transaction records onchain cannot confer a corporate veto that issuers never possessed offchain. Corporate attempts to restrict technological deployment in secondary markets threaten to overturn decades of established securities law governing negotiable property rights.
Nonetheless, counterarguments raised by corporate issuers stem from legitimate operational and reputational anxieties. Executives like AMC chief executive Adam Aron argue that unapproved tokenized products may mislead retail investors into believing they own voting shares, blurring legal distinctions between direct ownership and unvoted synthetic claims.
Governance Risks and Conditions for Legal Validity
Custodial insolvency and asset segregation present further genuine concerns for market stability. As emphasized in federal rules on digital custody, inadequate reconciliation between offchain depository reserves and onchain token issuance could trigger catastrophic counterparty failure, inadvertently inflicting severe collateral damage on the referenced company’s brand and perceived stability.
If an offshore token issuer fails, disenfranchised retail holders often blame the public company whose ticker was marketed. Public corporations invest substantial capital maintaining transparent investor relations, and management rightfully fears that unregulated synthetic trading could introduce manipulative distortion into primary price discovery mechanisms.
The argument against corporate vetoes collapses if a tokenized product alters internal corporate governance obligations. If a sponsor demands that transfer agents record token transfers directly onto the official shareholder ledger or alters shareholder quorums, issuer consent becomes legally indispensable and non-negotiable under state corporate statutes.
Tokenized wrappers must also comply rigorously with federal anti-money laundering and customer identification standards. Legitimate third-party tokenization requires bankruptcy-remote custodial structures ensuring that underlying shares remain segregated from the operating assets of the issuing broker-dealer, eliminating systemic insolvency contagion risks.
Clear legal disclosures must separate the synthetic certificate from the underlying corporate enterprise. Brokerage platforms have an absolute duty to clarify that the underlying company neither sponsors nor endorses the digital product, eliminating any misleading impression of corporate affiliation or formal business partnership.
Conceding veto rights to corporate boards would stifle financial market modernization across international boundaries. Restricting synthetic access would isolate retail investors in emerging economies from Western capital markets, preserving legacy custodial monopolies that extract excessive intermediation fees from cross-border transactions.
Capital markets rely on the standardization of global negotiable contracts and predictable property laws. Allowing corporate boards to handpick authorized secondary trading venues would convert transparent public equity markets into fragmented private distribution franchises, undermining the foundational liquidity of public corporations.
Regulatory scrutiny must focus on custodial solvency verification rather than corporate market censorship. Securities regulators should mandate verifiable proof of physical equity reserves, ensuring that every circulating token matches segregated shares held in qualified depositories, instead of granting issuers anticompetitive veto rights.
If independent third-party reserve audits verify that token supply strictly matches segregated equity shares across custody accounts, legal challenges brought by corporate issuers will fail to establish actionable trademark or securities violations in federal courts over the next twenty-four months.
This article is for informational purposes only and does not constitute financial advice.